
Current Affairs
April 30, 2026
Housing Production Bounce
Home building shows signs of stabilization with March starts
By Dakota Smith
April 29, 2026 | 8:49 am CDT
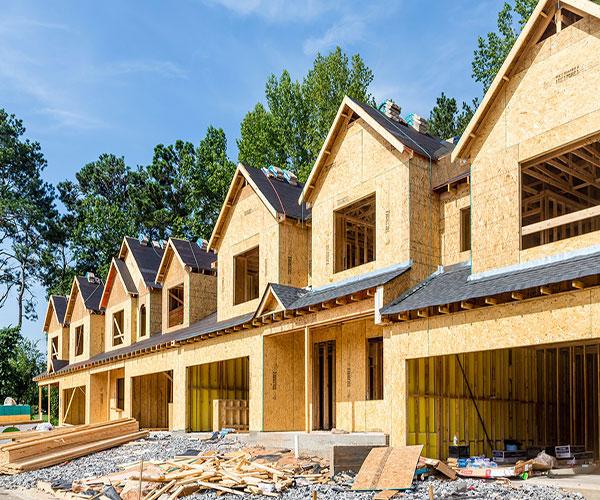
WASHINGTON, D.C. — Housing production bounced back in March as builders cautiously ramp up production despite ongoing headwinds.
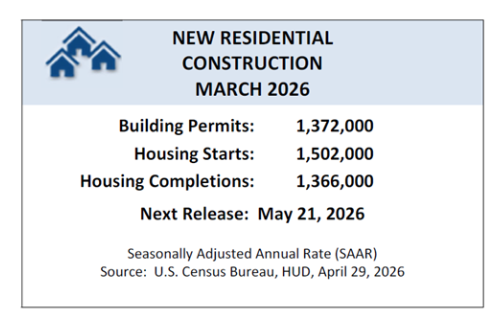
The March reading of 1.5 million starts is the number of housing units builders would begin if development kept this pace for the next 12 months. Within this overall number, single-family starts increased 9.7% to a 1.03 million seasonally adjusted annual rate and are up 8.9% compared to March 2025. The multifamily sector, which includes apartment buildings and condos, increased 13.3% to an annualized 470,000 pace and are up 15.5% compared to March 2025.
“Housing starts posted a solid rebound in March, suggesting builders are responding to pockets of improving demand despite ongoing affordability challenges, although activity remains sensitive to interest rate movements and construction costs,” said Bill Owens, chairman of the National Association of Home Builders (NAHB) and a home builder and remodeler from Worthington, Ohio. “Overall, the uptick in housing starts is a positive development for residential investment and signals that the sector may be stabilizing.”
“Single-family starts drove much of the monthly increase, indicating that builders are cautiously ramping up production to meet persistent inventory shortages in the resale market,” said Danushka Nanayakkara-Skillington, NAHB’s assistant vice president for forecasting and analysis. “While this is an encouraging sign, the pace of construction is likely to remain measured as builders continue to navigate elevated financing costs and labor availability. On a regional level, the Midwest continues to outshine the rest of county as the only region to have positive single-family starts growth.”
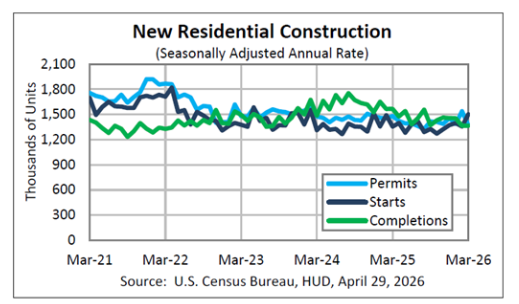
Overall permits decreased 10.8% to a 1.37 million unit annualized rate in March. Single-family permits decreased 3.8% to an 895,000-unit rate and are down 7.9% compared to March 2025. Multifamily permits decreased 21.5% to an annualized 477,000 pace and are down 6.3% compared to March 2025.
Looking at regional permit data on a year-to-date basis, permits were 15.4% higher in the Northeast, 1.1% higher in the Midwest, 9.1% lower in the South and 6% higher in the West.
The number of single-family homes under construction is at 587,000 units while the number of apartments under construction is at 677,000 units.
April 15, 2026
Driver Availability Affecting Freight Market
Cass data shows freight market tightened further in March
TL linehaul rate index up 15 straight months
· Tuesday, April 14, 2026

March data from Cass Information Systems showed freight shipment declines narrowed while rates continued to move higher.
Cass’ (NASDAQ: CASS) multimodal shipments index increased 3% sequentially in March (up 1% seasonally adjusted), building on a 10.4% increase in February (plus-4.3% seasonally adjusted). The index was down just 4.5% year over year in the recent month, the smallest y/y decline since June. On a two-year comparison, freight volumes tracked by Cass were off less than 10%.
| March 2026 | y/y | 2-year | m/m | m/m (SA) |
| Shipments | -4.5% | -9.5% | 3.0% | 1.0% |
| Expenditures | 4.2% | 2.1% | 4.9% | 2.4% |
| TL Linehaul Index | 1.8% | 3.4% | -0.5% | NM |
Table: Cass Information Systems (SA – seasonally adjusted)
The dataset has lagged other indicators, which are showing a more upbeat demand environment.
Cass data includes a significant mix of less-than-truckload transactions. Less-than-truckload demand is weighted to the industrial economy, which has been under pressure for the majority of the past three years. However, an LTL inflection may be nearing as the Purchasing Managers’ Index for manufacturing has signaled growth in the first three months of the year.
The Tuesday report said the shipments index is “starting to catch up with other indicators” as “tightness in dry van truckload (TL) conditions is starting to radiate to other markets.” The index is expected to be off 5% y/y in April, assuming normal seasonal patterns hold, moving into positive territory in the back half of the year (plus-1.5% is the current forecast).
Even with the volume headwind, Cass’ expenditures index, which measures total freight spend including fuel, increased 4.9% from February (up 2.4% seasonally adjusted). A 4.2% y/y increase during the month coupled with the 4.5% decline in volumes implies actual freight rates were roughly 9% higher in the month. However, changes in freight mix can alter the implied rate assumption.

The report said a recent survey of midsize and large fleets showed some tightening in driver availability as new non-domicile CDL rules took effect in the month.
“Driver availability is a key component of capacity in the market, and additional scarcity seems likely, supporting higher freight rates,” the report said.
Cass’ TL linehaul index, which tracks rates excluding fuel and accessorial surcharges, increased 1.8% y/y in March, marking 15 consecutive y/y increases. A modest 0.5% step down from February was the first sequential decline in seven months. (The dataset includes for-hire spot and contract rates.)

Higher diesel fuel prices, which pushed some operators to the sidelines, offset incremental capacity availability as carrier networks recovered from severe winter storms, the report said.
“Considerable increases in contract rates are likely for the truckload market. After a four-year bottoming phase of the for-hire cycle, we believe we’ve moved to the early cycle phase where capacity becomes short and rates rise.”
Data used in the indexes comes from freight bills paid by Cass, a provider of payment management solutions. Cass processes $37 billion in freight payables annually on behalf of customers.
March 23, 2026
Trucking Update
National trucking capacity is about to tighten significantly
· Sunday, March 22, 2026

The freight market momentum is building at a rapid clip. National dry van spot rates — tracked via the SONAR National Truckload Index (NTI.USA), the 7-day moving average of booked rates including fuel — have broken out to a new cycle high of $2.89 per mile. This represents the strongest level since 2022 and confirms the market’s shift toward carriers is gaining real traction.

Chart: SONAR National Truckload Rate Index (NTI.USA) GoSONAR.com
Even more telling: rates jumped $0.12 per mile in the past week alone. That’s a sharp weekly gain that underscores accelerating tightness and carrier pricing power. Spot rates have now recaptured roughly $0.50–$0.60 per mile net of fuel over recent months, climbing from the low $2.00s that defined much of 2023–2024. We’re witnessing 20–25% year-over-year recovery in key lanes and metrics, with volumes holding at multi-year highs reminiscent of late 2022.
This isn’t isolated noise — it’s driven by fundamentals. The return of industrial demand remains the core engine, with stronger manufacturing signals, flatbed activity, and overall domestic freight resilience putting sustained pressure on a shrunken truckload supply. Multi-year carrier attrition (exits, driver regulations, and structural challenges) has left capacity thin, making the market highly responsive to any demand pickup. National tender rejection rates sit stubbornly in the low-to-mid teens (around 13–14% recently), with the Midwest still leading above 18% and tightness now spreading more broadly.
Seasonal layers are piling on:
- Produce season is ramping in major growing regions.
- Construction is accelerating as weather improves.
- Gardening and home improvement demand is building.
- Beverage season is gearing up for warmer months.
These verticals compound the industrial rebound, further squeezing available trucks.
The West Coast awakening adds a powerful pull. Chinese New Year landed later this year (February 17, 2026, vs. earlier in prior cycles), prolonging the post-CNY slowdown and keeping Southern California unusually loose into early March (outbound rejections below 5%). But the rebound is hitting hard now: inbound containers are surging, outbound tenders are recovering, and rejections are set to rise meaningfully.

This creates a classic “magnet” for capacity. Long-haul carriers chase West-to-East port loads for their superior length of haul (1,500–2,000+ miles per move) versus shorter eastern runs that demand multiple loads for equivalent paid miles. As trucks reposition westward from Midwest/Southeast corridors (along I-35 and parallels) to capture higher-paying outbound freight via I-20 and I-40, interior markets face no relief — expect even tighter conditions back east. The Midwest’s industrial strength and elevated rejections mean any capacity drain will intensify pressure, not ease it.
Broader indicators align:
- Tender rejection rates remain high nationally, with seasonal builds accelerating the spread.
- Dry van spot rates continue rising on resilient volumes and persistent constraints.
- Ocean bookings are starting to recover sharply from Chinese New Year
The bottom line: Spring 2026 is igniting hotter and earlier than recent years. The $2.89 cycle high — fueled by a $0.12 weekly jump — reflects tightening capacity, resurgent industrial demand, seasonal verticals firing up, and the delayed-but-powerful post-CNY import surge creating synchronized tightness. Shippers unprepared for higher costs are under immediate strain, with routing guides tested early. Carriers positioned for West Coast outbound, industrial, and seasonal lanes are capturing the gains as capacity reallocates — but back east, conditions are set to tighten further as carriers shift their focus towards the West to East longhaul.
Monitor SONAR outbound rejections and spot rates from Southern California over the next 2–4 weeks, alongside Midwest/Southeast trends. The speed of this spread will show how broad and sustained the impact becomes.
The spring shipping season is just getting started — and it’s going to be a hot one.
March 22, 2026
China Responds to Record Trade Surplus
China vows more open economy in bid to boost confidence
ByLiam Mo and Ryan Woo
March 22 2026 – 8:00am

China has faced tensions with major trading partners over its record $A1.7 trillion trade surplus. Photo: EPA PHOTO
Chinese Premier Li Qiang has pledged to further open up the economy and fully implement national treatment for foreign enterprises as the country seeks to reassure the outside world amid rising global trade tensions.
China will import more high-quality foreign goods and work with all parties to promote optimised and balanced trade development and expand the global trade pie, Li told the China Development Forum in Beijing, state media reported on Sunday.
The annual two-day forum, which concludes on Monday, allows Beijing to lay out its economic vision and investment opportunities to foreign business leaders, Chinese officials, economists and academics.
This year’s gathering comes as the world’s second-largest economy faces rising tensions with major trading partners over 2025’s record $US1.2 ($A1.7) trillion trade surplus.

Premier Li Qiang says China is committed to being a “harbour of stability” for the world economy. (EPA PHOTO)
Challenges for Beijing are aplenty, including deflecting concerns from an increasing number of global capitals about China’s trade practices and overcapacity, as well as their overreliance on key Chinese products.
While Li’s speech did not appear to directly mention the surplus, his pledges indicate an awareness that the issue could disrupt international relations at a time when China has reached a temporary truce with the US on trade.
US President Donald Trump last week postponed a trip to Beijing to meet with Chinese President Xi Jinping due to the Iran war, delaying an effort to ease tensions between the world’s two biggest economies.
In a separate speech at the forum, China’s central bank governor Pan Gongsheng also sought to alleviate concerns surrounding the trade surplus.
“Analysing global economic imbalances requires looking not only at trade in goods but also services, and not only at the current account but also the financial account,” Pan said, according to a transcript of his speech published by the People’s Bank of China, adding that China is the country with the largest goods surplus but also the largest services deficit.
China has no need and no intention to gain trade competitive advantage through currency depreciation, Pan said.
Senior executives attending include those from Apple, Samsung Electronics, Volkswagen, chipmaker Broadcom Inc, industrial conglomerate Siemens, chemical producer BASF and pharmaceutical firm Novartis.
There were no Japanese company executives on the guest list on the forum’s website.
said foreign firms would be treated in the same way as domestic ones, allowing enterprises from all countries to develop with confidence and realise their ambitions in China.
In a separate meeting, Commerce Minister Wang Wentao told business leaders from a US pharmaceutical trade group and executives from five major multinational drug companies that China would strengthen intellectual property protection and improve policy transparency.
Australian Associated Press
March 22, 2026
IEEPA Duties Refund System
CBP has provided another update to the U.S. Court of International Trade on the development of its new ACE-based refund system for IEEPA duties, known as CAPE (Consolidated Administration and Processing of Entries).
While progress is being made, the system is still under development and not yet ready for deployment.
Latest Development Status
As of March 19, CBP reports the following progress:
- Claim Portal: 73% complete (testing underway)
- Mass Processing: 45% complete (validations and tracking in development)
- Review & Liquidation/Reliquidation: 80% complete (now in testing phase)
- Refund Processing: 63% complete (including refund consolidation functionality)
According to CBP, the system is now moving into more advanced testing phases, which are required before it can go live.
What This Means for Importers
Once operational, CAPE will allow importers and brokers to:
- Submit refund requests directly through a new ACE portal interface
- Have IEEPA tariffs automatically removed and duties recalculated
- Receive consolidated refunds at the importer level, including applicable interest
CBP also confirmed it is building functionality to track processing history and validate entries, which may impact which entries are eligible in early phases of the rollout.
Key Takeaway
Although progress continues, this update confirms that the refund system is still several weeks away from being fully operational.
In the meantime, importers should continue preparing by:
- Reviewing entries that may be eligible for refunds
- Ensuring ACE accounts are properly configured
- Completing ACH refund setup to avoid delays once payments begin
 Everchem Updates Archive
 Sign Up for Email Updates