
Current Affairs
March 19, 2026
Push Back
Small businesses are pushing back against private equity
Story by Michael Sasso and Saijel Kishan
(Bloomberg Businessweek) — Jay Cunningham says he’s fielded hundreds of calls and emails over the years from private equity firms poking around his Atlanta-area plumbing business. He wagers he could fetch tens of millions of dollars for Superior Plumbing, freeing up time for him to see his grandkids, say, or travel more to New York. But Cunningham refuses to make a deal with a buyout firm. Going from independent to PE-owned, he says, would be bad for his employees—including several of his adult children—as well as the wider community. “I’ve resisted selling, because of the people that work for me,” Cunningham, 64, says, adding that shoppers, too, are starting to boycott PE-backed companies if they’re aware the ownership has changed. They understand “that when these firms are getting gobbled up, it’s less favorable for the customer.”
For at least a decade, private equity has been encroaching on America’s mom and pop businesses, the backbone of the US economy, scooping up independent roofing contractors, veterinary practices, health clinics and other operators at a rapid clip. Now a PE pushback is brewing among small-business owners such as Cunningham, who are increasingly refusing to take part—and making sure everybody knows it, loudly touting their antibuyout stances and locally owned credentials.
Cunningham’s Superior Plumbing, for instance, has been advertising on electronic billboards across metro Atlanta that it’s “Still Locally Owned & Operated.” (It might as well read, “We’re Not Private Equity.”) In central Florida, Next Dimension Construction & Roofing posted a sleek video on social media warning about PE-owned businesses “run by investors who’ve never set foot in your neighborhood.” Some smaller-scale financiers see an opportunity in the backlash. Mark Peterson, a self-described “anti-PE” investor, buys minority stakes in small landscape and heavy construction businesses to help them stay independent without needed backing from new-to-the-sector investors who parachute in from faraway finance hubs, wearing suits to the worksite. “Boots before spreadsheets,” says Peterson, owner of Blue Collar CFOs in Idaho.
Spanning HVAC contractors in Texas and snow plow operators in Illinois to pest control businesses in New Jersey and electricians in Ohio, owners are increasingly sounding the alarm against PE, warning that buyout firms’ cost-cutting and debt-heavy deals are hollowing out the US’s small-business sector. Resistance to buyout deals has existed to some degree ever since Wall Street started invading Main Street with its typical PE playbook: Buy companies in fragmented industries, consolidate them in a “roll-up” strategy, improve their cash flow and sell them for a profit in a few years. But now the opposition appears to be intensifying, especially as baby boomer business owners prepare to sell their homegrown companies in what’s been dubbed an impending “silver tsunami.”
Roughly a quarter of small-business owners in the US are 65 years or older. As they prepare to retire, more than a million viable small and midsize companies will be up for sale by 2035, together worth as much as $5 trillion, according to a February report by the McKinsey Institute for Economic Mobility. These “owners have put a lot of sweat equity into their businesses. It’s part of their identity,” says Michael Strain, a director of economic policy studies at the American Enterprise Institute, a conservative think tank. So when PE comes calling, “there’s definitely a backlash.”
At the same time, the spread of software that digitizes scheduling, billing and customer service for even the most niche sectors has opened the door for PE firms to enter markets beyond health care and housing, where they already hold large positions. For instance, traffic-flagging companies, which help wave motorists through road projects, are seeing a surge of PE interest in the past two years. “We get notices every week that another firm has been acquired,” says Stacy Tetschner, chief executive officer of the American Traffic Safety Services Association, a Virginia-based trade group. Buyouts have been so hot in the landscaping industry that trade magazine Landscape Management introduced an annual mergers and acquisitions scorecard edition a year ago, editor-in-chief Scott Hollister says.
Software vendor ServiceTitan Inc., which has roughly doubled its revenue since 2023, to almost $1 billion, promotes “hypergrowth” opportunities for PE firms focusing on the trades. (ServiceTitan, based just outside of Los Angeles, didn’t respond to requests for comment.) Putting a recently acquired small business on such a software platform, which might let the new owner tap virtual customer service agents and automate scheduling, is usually one of PE’s first moves, says Robert Tymowski, an investment banker at Livingstone Partners LLC in Chicago. Home service companies never had big numbers of back-office staff, but they’re likely to shrink further with the growth of artificial intelligence, says Terry Tillman, a software analyst at Truist Securities Inc. in Atlanta. “It is a selling point,” he says. “Do more with less.”
In fact, going digital is such a big part of the PE playbook that customers mistakenly assumed Yossi Wachtel had taken a buyout after he upgraded the systems at his plumbing business in the Los Angeles area. Wachtel added branded trucks, introduced a digital scheduling system and began sharing technicians’ bios and photos with clients before visits, all in a bid to distance his company from the old caricature of a plumber wearing sagging pants exposing his backside. But those improvements backfired when a customer replied to a maintenance follow-up message asking to be removed from his list because they didn’t “do business with private equity owned companies,” says Wachtel, founder of Monkey Wrench Plumbing, Heating, Air & Electric. Now he instructs technicians to emphasize the operation’s family ownership whenever they’re on a job.
Supporters of private equity are quick to point out the benefits of the industry’s model. Private ownership can bring in capital, helping to strengthen businesses and create jobs; it can also help companies innovate and modernize. Some PE firms today even encourage the small-business founder to keep a minority stake in the company, hoping to preserve its culture. Buyouts in businesses worth $100 million or less totaled $89 billion last year, up 56% since 2015, according to data firm PitchBook. Will Dunham, president of the American Investment Council, an advocacy group for the private equity industry, says buyout firms are a key driver of growth for small and midsize businesses in the US. “Research shows that PE-backed businesses consistently boast higher wages and benefits, more job creation and stronger revenue than their non-PE-backed peers,” he says.
But critics point to the darker side: higher prices for customers, a singular focus on the bottom line, potential layoffs, less benefit to the community. In the New Orleans area, small-business owner Craig Jacomine has been encouraging other operators to consider local partnerships to help them become more streamlined and professional instead of selling to private equity, especially after seeing the fallout firsthand at competitors who made deals: a loss of control, higher debt leverage and payout structures that can limit what sellers ultimately get if they don’t meet performance targets.
“If we keep going down this route,” says Jacomine, who says he turns down nonstop calls from buyout firms looking to acquire his electric generator company, “everyone is going to be buying from one company—and that’s it.”
Beware “Another bite of the apple!”
Editor
March 15, 2026
European Polyol Analysis
Europe’s Polyether Polyol Industry: Can It Withstand Another Market Shock?
PUdaily | Updated: March 6, 2026
The closure of the Strait of Hormuz has collided with a European polyol industry already operating under severe structural pressure, squeezed by low-priced Asian imports, shuttered domestic capacity, and energy costs far above those faced by competitors in Asia or the Middle East. The market, in the words of one participant this week, is “muy nervioso.”
MARKET SNAPSHOT — 5 MARCH 2026

PRICE TRAJECTORY: TWELVE MONTHS OF STRUCTURAL PRESSURE
The chart below captures the industry’s recent price trajectory. Spot prices for flexible slabstock polyol in Western Europe opened March 2025 at €1,275/t and rallied sharply to €1,495/t in mid-April on seasonal restocking. Prices then declined steadily, falling nearly 29% to a trough between €1,000 and €1,065/t by early October, a level at which most non-integrated European producers operate at very tight margins.
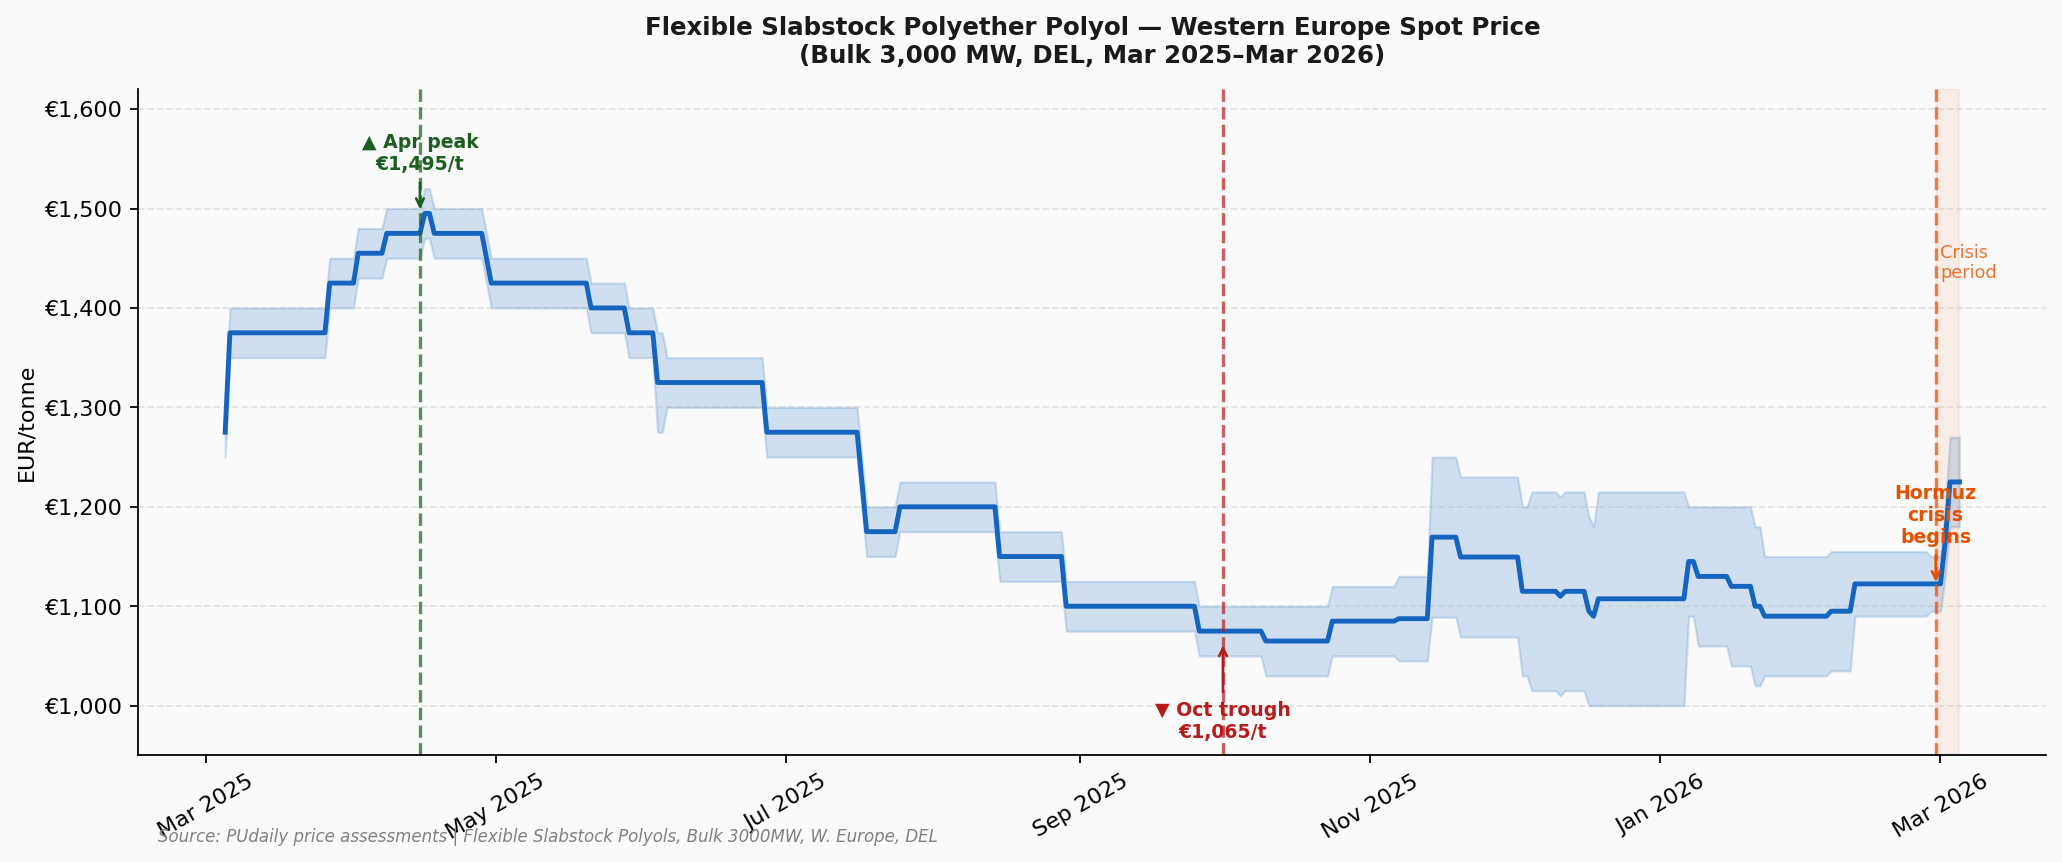
Chart 1 — Flexible Slabstock Polyol spot price (mid-range), Western Europe, Mar 2025–Mar 2026.
Source: PUdaily price assessments.
THE INDUSTRY BEFORE THE CRISIS: ALREADY UNDER STRUCTURAL PRESSURE
Before a single missile was launched or a tanker rerouted, the European polyether polyol sector was already facing significant structural disadvantages that years of industry lobbying had failed to resolve. Understanding this baseline is essential to explaining why the current crisis may represent more than a temporary disruption.
- Energy costs: a structural disadvantage
European chemical producers have operated with a persistent energy cost disadvantage compared with global peers. Throughout 2024 and 2025, gas prices in Europe remained several times higher than in the United States. Data from the European Chemical Industry Council (Cefic) indicate that at the start of 2025, European gas prices were approximately 3.3 times higher than those in the US.
For an energy-intensive process such as polyether polyol production, which requires propylene oxide feedstock and significant utilities for reactor temperature control, energy pricing is not a marginal cost factor. It represents a structural competitive constraint that compounds whenever feedstock costs increase.
- The Asian import ceiling
Trade statistics also illustrate growing competitive pressure. EU customs data show that between 2023 and 2025 import volumes increased while average unit values declined. The practical result is a price ceiling on commodity grades of polyether polyols.
European producers cannot sustainably price above the landed cost of imported Asian material, yet their production costs frequently exceed that level at non-integrated sites. This dynamic has placed persistent downward pressure on margins.
2025: the year of capacity rationalisation
The market response to this structural squeeze has been a wave of closures and production rationalisations that have significantly reduced Europe’s shock-absorption capacity.
Dow Chemical confirmed the shutdown of its Tertre (Belgium) polyols facility, representing approximately 94,000 t/year of commodity-grade capacity, citing energy costs, regulatory pressures, and sustained import competition. The site is expected to cease operations by the end of March 2026.
INEOS closed propylene oxide and propylene glycol production at its Cologne site on an indefinite basis, signalling a structural adjustment rather than a temporary market response.
LyondellBasell and Covestro also confirmed the permanent closure of the PO/SM “PO11” unit at Maasvlakte in Rotterdam, referencing global overcapacity and Europe’s cost disadvantage.
These closures reduce Europe’s ability to buffer supply disruptions and weaken the economic case for maintaining integrated propylene oxide supply chains within the region.
THE HORMUZ SHOCK: THREE TRANSMISSION CHANNELS
The military escalation involving Iran that began at the end of February 2026 has disrupted the European polyol supply chain through three simultaneous channels. Individually, each would be manageable. Combined, they create significant uncertainty across the market.
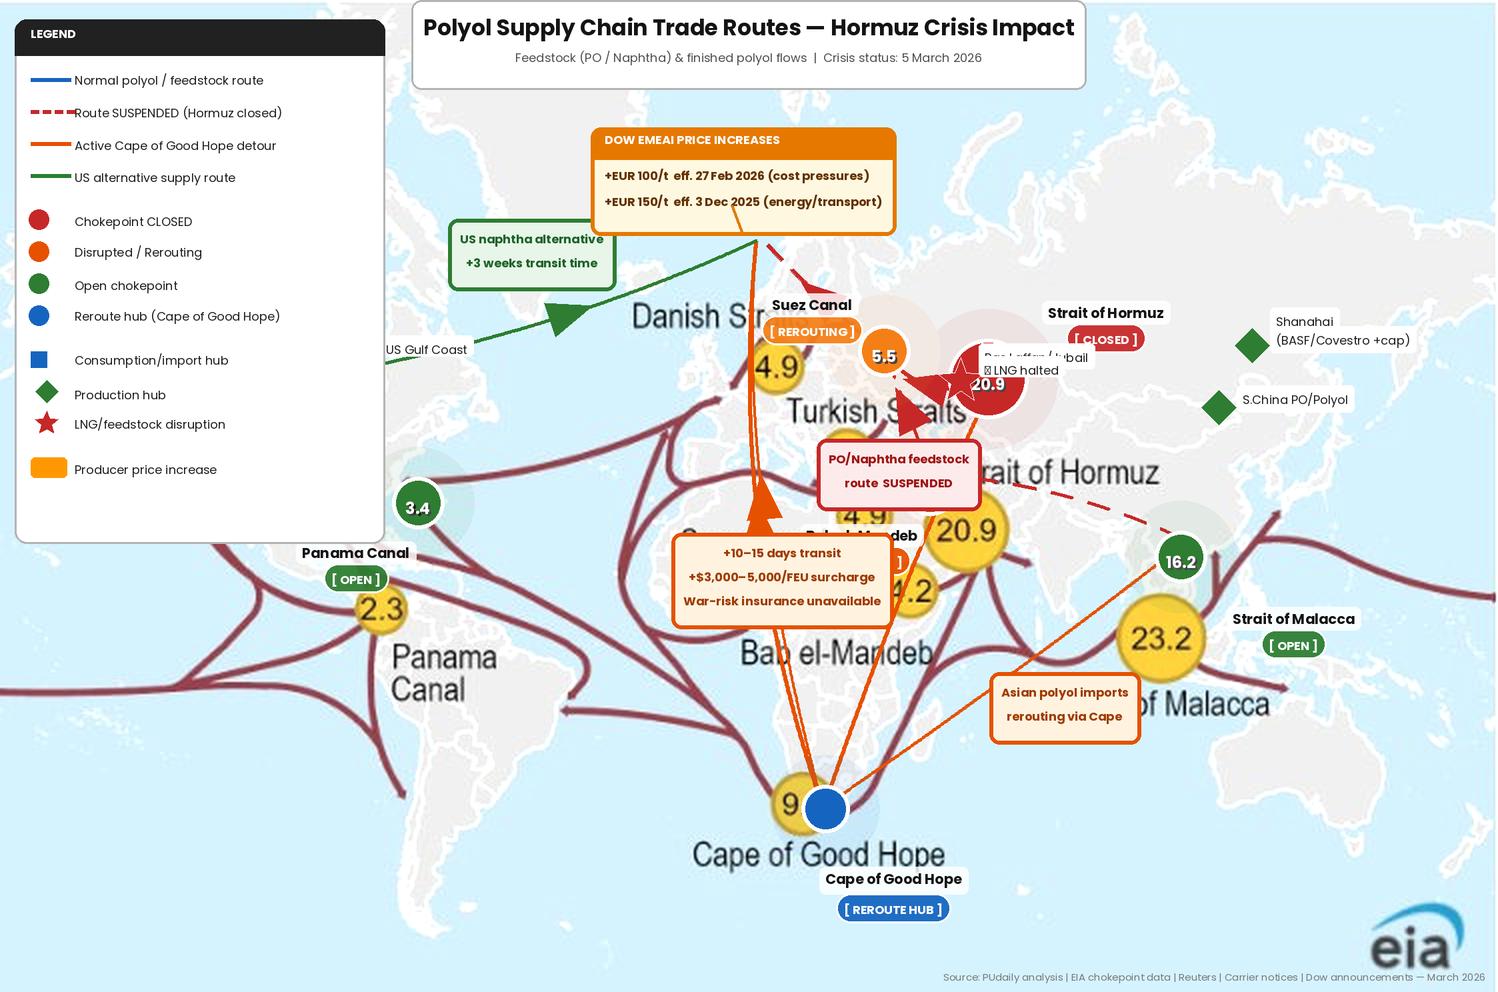
Map, Global petrochemical trade routes and chokepoint status as of 5 March 2026. Red dashed = suspended (Hormuz closure); orange = active Cape of Good Hope detours; green = US alternative. Dow EMEAI price increases annotated.
Source: PUdaily analysis, EIA, carrier notices.
- Channel 1: Logistics disruption
Major shipping companies including Maersk, MSC, CMA CGM and Hapag-Lloyd have suspended transits through the Strait of Hormuz. Vessels are being rerouted around the Cape of Good Hope, adding approximately 10–15 days to transit times and triggering emergency freight surcharges.
War-risk insurance has either become unavailable or prohibitively expensive. Reports indicate that several vessels have been struck near the strait and shipping intelligence suggests that a large number of vessels remain stranded in the surrounding area.
CMA CGM has introduced emergency conflict surcharges of up to $4,000 per container. For polyols transported in ISO tanks or bulk shipments, the per-tonne freight impact follows a similar logic.
Buyers who in recent years reduced inventories and relied on just-in-time imports from Asia or the Middle East now face supply chain vulnerability. Market participants report rising freight rates, although confirmed figures remain limited as the situation continues to evolve.
- Channel 2: Energy market disruption
The energy dimension of the crisis may have even deeper structural implications. QatarEnergy suspended LNG production following strikes affecting facilities at Ras Laffan and Mesaieed. Qatar supplies roughly 20% of global LNG, and the disruption immediately tightened global gas markets.
European gas storage levels were already relatively low for this time of year, around 30%. As supply concerns intensified, TTF futures rose sharply, increasing approximately 70% within days and peaking above €60/MWh. Some market estimates suggest that under a sustained one-month Hormuz disruption scenario, TTF prices could approach €70–€75/MWh.
For polyol producers whose margins were already thin before the crisis, such energy cost increases represent a severe economic challenge. Each increase in gas prices directly erodes margins in a market where selling prices remain constrained by international competition.
PRIMARY SOURCE — DOW EUROPE: PRICE INCREASE ANNOUNCEMENTS
3 December 2025 — Dow Europe GmbH announced an immediate increase of +€150/t for all polyether polyol grades in EMEAI (Europe, Middle East, Africa, India), effective immediately or within shortest time permitted by contract. Dow cited escalating raw material, energy, and transportation costs pressuring production economics.
27 February 2026 — Dow Europe announced a further +€100/t increase for all polyether polyol series in EMEAI, effective immediately. Dow cited current cost pressures and evolving supply-demand dynamics — the announcement landing one day before the outbreak of military conflict in Iran on 28 February, which further intensified expectations among polyurethane raw material suppliers.
Combined announced increase: +€250/t since December 2025. Source: PUdaily, Dow Europe GmbH announcements.
- Channel 3: Naphtha and propylene pressure
The naphtha disruption is affecting multiple regions simultaneously. Asian petrochemical producers are also facing feedstock supply risks as Middle Eastern export flows are disrupted.
Reports indicate that several Asian petrochemical companies are considering run rate reductions or temporary shutdowns. Indonesia’s Chandra Asri has declared force majeure on certain contracts, while Japanese producers have cancelled import tenders for April naphtha cargoes.
Asia typically imports around four million tonnes of Middle Eastern naphtha per month. South Korea alone sources roughly 54% of its naphtha supply through routes that pass the Strait of Hormuz.
If Asian steam crackers begin reducing operating rates due to feedstock constraints, this could temporarily reduce export pressure on European markets. However, the impact would depend on how long the disruption persists and how quickly alternative supply routes are secured.
THE MARGIN SQUEEZE: SCENARIO ANALYSIS
Even under rapid geopolitical de-escalation, many European producers remain only marginally profitable on commodity grades.
Under prolonged disruption, the gap between production costs and achievable selling prices may widen further, compressing margins to levels that historically have triggered additional plant closures or force majeure declarations.
The key dynamic is asymmetry. Cost shocks related to energy, logistics, and feedstocks transmit rapidly and with high certainty. Price recovery, however, is constrained by the competitive ceiling imposed by imports.
Even if Asian producers experience their own cost increases, they often have greater scale, integration, and alternative supply options that allow them to absorb temporary margin compression more easily.
IMPLICATIONS FOR MARKET PARTICIPANTS
- Buyers and downstream processors
For polyurethane processors, including foam, automotive, and insulation producers, security of supply is rapidly becoming a priority alongside price management. Buyers that have relied heavily on spot imports and minimal inventories face the greatest risk of supply disruption.
Market participants report increasing concern about availability, which may drive precautionary inventory building in the near term. Buyers with long-term supply contracts or domestic supplier relationships are comparatively better positioned.
- Traders and distributors
The arbitrage trade that has been profitable for the past 18 months, Asian polyol into Europe on improving freight and weak spot prices, is temporarily shut. Logistics are disrupted, insurance is expensive or unavailable, and transit times have extended. Traders who have cargo already en route face uncertainty about delivery timing and war-risk exposure. Those with European inventory have pricing power for the first time in months, though the window may be narrow. Watch for the resumption of Asia-to-Europe flows once routing clarity and insurance markets normalize, that is when the structural price ceiling re-asserts itself.
- European producers
The remaining integrated European producers, those with captive propylene oxide supply and flexible energy management, have a genuine competitive advantage in this environment. They have product. They have defined supply chains. They are not exposed to Hormuz rerouting risk on their feedstocks. The temptation will be to press that advantage on price, and the market would likely accept some increase given availability anxiety. The risk is overreaching: if the disruption resolves quickly and Asian volumes resume, any price gains will reverse sharply and relationship damage with key accounts will persist.
The deeper strategic question, beyond this crisis, is whether these closures and this disruption finally provoke a policy response that meaningfully addresses the energy cost differential. The European Commission’s Chemical Action Plan and Clean Industrial Deal rhetoric has been positive; the concrete impact on production economics has been minimal. That calculus may be changing.
OUTLOOK: KEY FACTORS TO MONITOR
Given the rapidly evolving geopolitical environment, specific price forecasts remain highly uncertain. Instead, several key indicators should be closely monitored:
- Hormuz shipping conditions – Any diplomatic progress reopening shipping lanes would quickly reduce freight and insurance costs.
- Qatar LNG production – A resumption of output from Ras Laffan would significantly ease pressure on European gas markets.
- Asian steam cracker run rates – Feedstock shortages in Asia could temporarily reduce export competition.
- European contract negotiations – Quarterly settlement discussions may reflect stronger cost-pressure arguments from producers.
- Potential force majeure declarations – Any disruptions to feedstock supply could have immediate market consequences.
THE BOTTOM LINE
Europe’s polyether polyol industry was already operating without a margin buffer when the Hormuz crisis began. The simultaneous shock to energy costs, feedstock logistics and import availability has removed the assumption of resilience that was still, however weakly, attached to remaining European production assets. The near-term price signal is upward, driven by anxiety, not demand recovery. The medium-term risk is that the disruption proves short-lived, Asian imports resume at low unit values, and the brief window of European producer advantage closes before any structural relief arrives. The permanent question, whether Europe retains a commodity polyol industry at all, has not been answered by this crisis. It has merely been made more urgent.
DATA NOTES & SOURCES
Polyol price data: PUdaily price assessments, Flexible Slabstock Polyols Bulk 3,000 MW, Spot, Western Europe, DEL, EUR/t. Price shown as mid-point of assessed range. | EU import data: Eurostat/UN Comtrade HS 390720 (“other polyethers, primary forms”) — used as directional proxy; not identical to polyether polyol trade classification. | Energy data: TTF front-month, EIA STEO, Cefic. | Naphtha: Reuters, 4 March 2026. | Shipping: Drewry WCI, carrier notices. | Capacity data: company announcements. | Market colour: anonymised primary sources, 5 March 2026. | All scenarios in Chart 3 are illustrative cost-build estimates and do not constitute price forecasts.
March 10, 2026
BASF introduces biomass balance polyether polyol product portfolio for the sleep products, automotive and CASE industries
WYANDOTTE, MI – MARCH 10, 2026 – BASF has announced the first commercial production of its biomass balance (BMB)[1]polyether polyols in North America, manufactured at the company’s Verbund site in Geismar, Louisiana. The new product line broadens BASF’s portfolio of sustainable polyurethane raw materials and represents a significant milestone in advancing the company’s sustainability goals.
The BMB polyether polyols are certified under the internationally recognized ISCC PLUS certification[2], ensuring full traceability and verification of sustainable biomass inputs across the value chain. Using the biomass balance approach, BASF replaces a share of fossil-based feedstocks at the beginning of the production process with renewable, bio‑circular materials, while maintaining identical product quality and performance compared with conventional polyether polyols.
Polyether polyols play a central role in polyurethane chemistry. They are a primary raw material that reacts with isocyanates to create polyurethane polymers. BASF’s biomass balance polyols provide a drop‑in solution that helps customers reduce the product carbon footprint (PCF) of flexible foam formulations used in countless industrial applications. Because BMB products retain the same specifications and processing characteristics as their fossil-based counterparts, manufacturers can adapt quickly without operational disruption.
“Expanding our BMB portfolio to include polyether polyols produced in Geismar further strengthens the trust our customers place in BASF to deliver reliable, sustainable solutions,” said Stefan Doerr, BASF Senior Vice President, Monomers North America. “Customers in the sleep products, automotive, and CASE industries can transition to these new solutions without any reformulation or process changes – making the shift both seamless and immediately actionable.”
BASF’s Monomers division continues to advance an ambitious sustainability roadmap, including the development of low‑PCF and circular product options across its major product lines. The launch of ISCC PLUS-certified BMB polyether polyols in North America complements the division’s existing BMB isocyanate offerings and reinforces BASF’s integrated approach to more sustainable polyurethane systems.
To learn more about BASF’s Biomass Balance portfolio and certification process, please visit us at https://chemicals.basf.com/north-america/en/Monomers/isocyanates-and-polyols/about-us/sustainability
[1] Biomass balance method (BMB): Fossil raw materials required for the manufacture of BASF products are replaced with renewable feedstock along the integrated production chain. The corresponding share of renewable material is attributed to the specific sales product via a certified mass balance approach. Production methods of this kind save fossil resources and reduce CO2 emissions at the same time. Renewable feedstock is not traceable in the BASF product.
[2] ISCC PLUS is a sustainability certification scheme for the use of sustainable biomass as raw material in the chemical industry. A certification according to this certification scheme confirms that the biomass used is sustainable and has been fed into the production system in the required amount. It also confirms that the sustainable biomass has been correctly attributed to the corresponding sales products. The certification is awarded on the basis of on-site audits conducted by independent auditors.
source: https://www.basf.com/us/en/media/news-releases/2026/03/P-US-26-11
March 5, 2026
Residential Furniture Orders Flat in 2025
Furniture orders finish 2025 flat despite December drop
March 4, 2026 | 8:43 am CST

Photo by Spacejoy on Unsplash.
HIGH POINT, N.C. — New residential furniture orders dropped 11% in December compared to the previous month, but were up 1% compared to the 2024 figure, according to the February issue of Furniture Insights. “Year to date through December 2025, new orders pulled even with 2024 ignoring the impact of tariffs/inflation,” said Mark Laferriere, assurance partner at Smith Leonard, the accounting and consulting firm that produces the monthly report.
“Certainly not what people were hoping for coming into 2025, but perhaps a relative win in light of the challenges presented by the year’s disruptions.”
Approximately one-half of participants reported increases in December 2025 compared to a year ago, he said.
December shipments were flat compared to 2024 figures, with one-half of survey participants reporting increases compared to the year prior, Laferriere added. Shipments also flat compared to November. Shipments ended the year down 1% compared to December 2024 year-to-date figures.
“December 2025 backlogs were down 2% compared to December 2024, and down 1% from November 2025 as shipments outpaced new orders,” he added.
Receivable levels were down 11% from November and down 9% from December 2024. Inventories were flat with November and up 4% from December 2024.
On a seasonally adjusted basis, sales at furniture and home furnishings stores in December were down 0.9% compared to November, and down 5.6% from December 2024. Year to date on a non-adjusted basis, sales were up 2.3%, compared to 3.0% last month, according to February’s Furniture Insights.
Sales at furniture and home furnishings stores in December 2025 were down 0.9% compared to November 2025 on a seasonally-adjusted basis, and down 5.6% from December 2024. Year to date on a non-adjusted basis, sales were up 2.3% (3.0% last month).
Commenting on economy and industry, Laferriere said, “This month we saw the Supreme Court strike down the tariffs imposed under the International Emergency Economic Powers Act, though they were quickly replaced with temporary tariffs of 10% (or 15%) that are generally lower than those imposed under IEEPA or otherwise negotiated, particularly for Asian countries. Certainly a lot still be determined on how these tariffs are unwound, potentially refunded and to who, what will ultimately replace them, then not to mention the operational burden on those within the industry who will get to once again deal with potentially resetting their cost and pricing structures ahead of the April Market.
“While the situation in Iran presents real-life human consequences, history has shown the impact of such conflicts on the stock market or consumer confidence to be generally short-lived. The more immediate concern to the economy and the industry would seem to be the impact of oil prices on container costs and discretionary income that drive consumer spending,” he added.
“On a brighter note, there is some good news coming out of housing with the affordability index improving across all regions, which coupled with the continued decline in interest rates could drive the increased activity within the industry for 2026 we’ve been looking for.”
.
https://www.woodworkingnetwork.com/furniture/furniture-orders-finish-2025-flat-despite-december-drop
March 4, 2026
US Chemical Companies “Net Beneficiaries”
US Chemical Companies “Net Beneficiaries” Of Middle East Energy Disruption Crisis
by Tyler Durden
Wednesday, Mar 04, 2026 – 05:45 AM
Bloomberg News headlines indicate that Iraq has begun shutting down oil output at Rumaila, the world’s largest “supergiant” oil field, while other Gulf states have idled some of the world’s largest refineries and major energy hubs following Iranian drone strikes. This signals that a massive energy disruption is set to hit global energy markets as the Strait of Hormuz remains paralyzed.
Goldman analysts led by Duffy Fischer have released a note assessing whether U.S. chemical manufacturers have exposure to Middle East energy disruptions. They find that “U.S. companies are likely to be net beneficiaries” of the Middle East conflict and the resulting energy disruptions.
Fischer pointed out that as oil prices rise, naphtha-based competitors in Europe and Asia are squeezed, while U.S. chemical makers that rely more on natural gas are relatively insulated due to domestic production. That, in turn, widens the U.S. margin advantage.
These U.S. chemical manufacturers use raw materials such as natural gas, crude oil liquids, salt, sulfur, and other minerals to produce products like:
- basic chemicals: ethylene, propylene, methanol, chlorine, ammonia
- plastics/resins: polyethylene, PVC, polyurethane inputs
- fertilizers: nitrogen, phosphate products
- industrial chemicals: solvents, coatings, acids, adhesives
- specialty chemicals: ingredients used in electronics, autos, construction, packaging, and consumer goods
Fischer explained:
The oil to gas ratio is a large driver of U.S. chemical production profitability. With oil prices increasing (see our Commodity team’s note and podcast), this will push up the price of naphtha, which is likely to increase the cost of European and Asian feedstocks. Since many naphtha crackers are currently near breakeven levels, that should force them to raise prices. This should lead the spot and export prices higher for U.S. product. The result would be an increase in U.S. margins as their natural gas feedstocks are not likely to be impacted. Lastly, while the industry believed that the March PE contract prices would roll flat, the events would significantly increase the possibility of U.S. producers achieving pricing in March.
Next, the analysts assess whether U.S. chemical manufacturers have exposure to the Middle East. They point out that Middle East disruptions would benefit U.S. chemical manufacturers.
Here’s how:
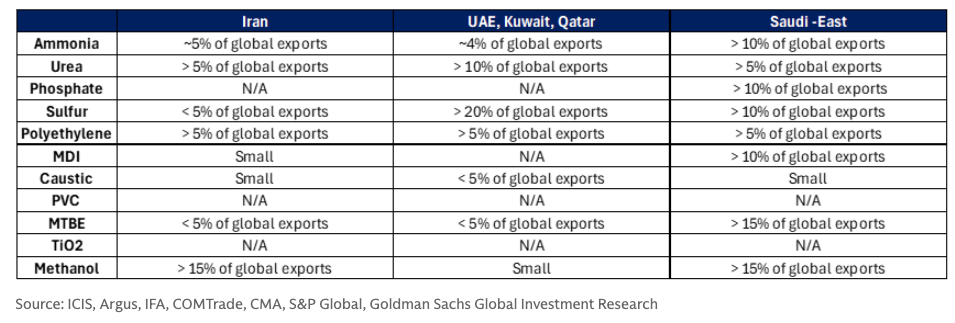
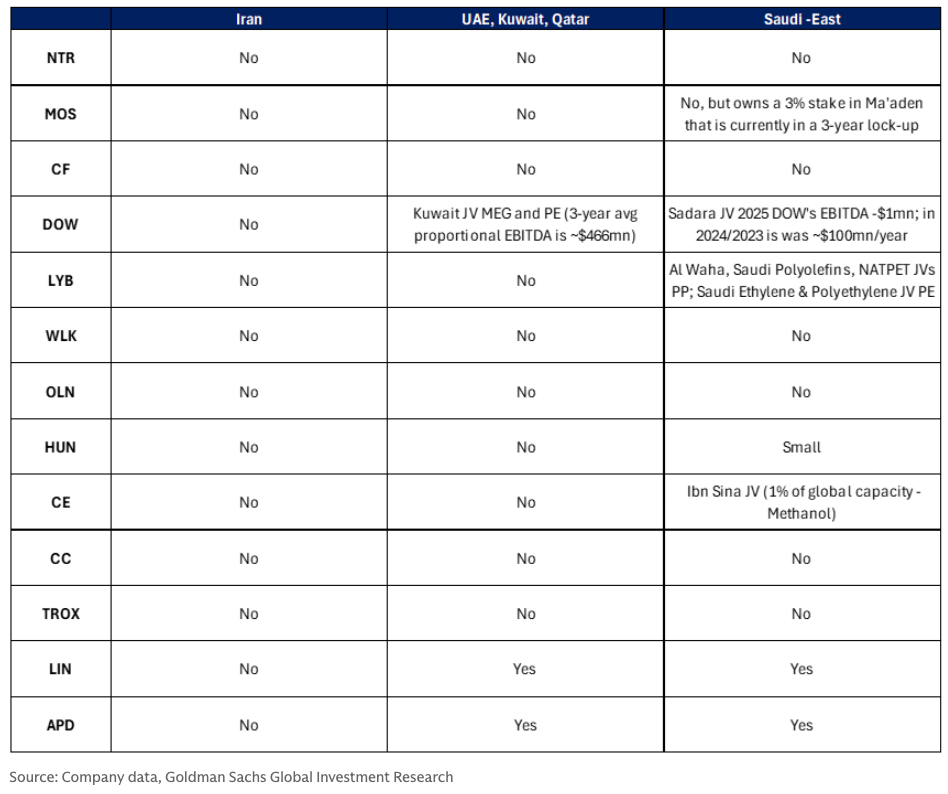
Significant amounts of competing chemical products are produced in the affected Middle East region. If this product is offline or is not able to ship then that would start to tighten global supply-demand and open up more volume opportunities for US producers. We look at three buckets of production (Iranian, UAE/Kuwait/Qatar, and Eastern Saudi Arabian). The impact on Iranian production is unclear and ships carrying production from Eastern Saudi Arabia, UAE, Kuwait, and Qatar through the Straight of Hormuz appear to be disrupted. Exhibit 1 shows the greatest impact to the least for impacted chemical chains: Nitrogen, Sulfur, Methanol, MTBE, Phosphate, Polyethylene, MDI, TiO2, Chlorovinyls. While U.S. companies are likely to be net beneficiaries, there are some U.S. companies with assets in the region that may see negative impacts. Barring any U.S. assets being kinetically impacted, the net should be positive for all U.S. chemical companies.
Exposure:
Regional Exports by Chemical Chain as a % of Global Exports
Company Asset Exposure to the Middle East
https://www.zerohedge.com/energy/us-chemical-companies-net-beneficiaries-middle-east-energy-disruption-crisis
 Everchem Updates Archive
 Sign Up for Email Updates

