
Current Affairs
February 12, 2026
U.S. Total Vehicle Sales History
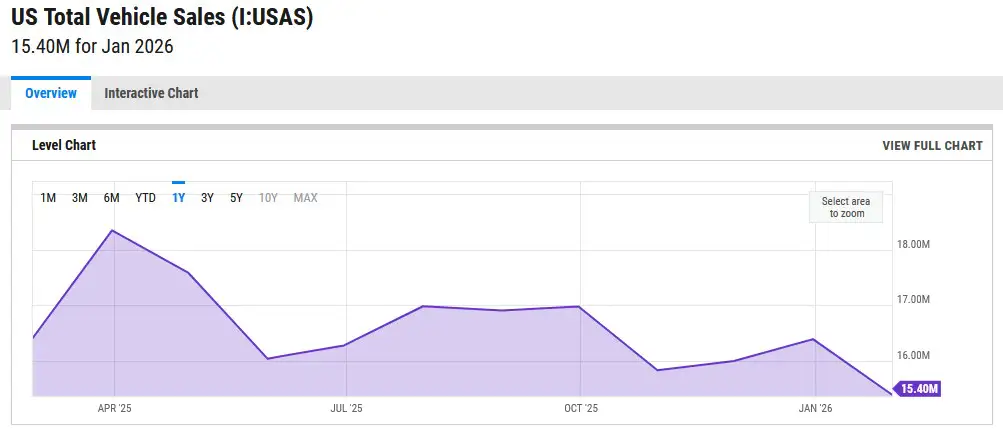
January 29, 2026
Positive News in Manufacturing
US Factory Orders Surged In November
by Tyler Durden
Thursday, Jan 29, 2026 – 10:06 AM
While sentiment is sagging to multi-year lows, ‘hard’ data is pushing growth forecasts higher (GDPNOW) and holding stocks at record highs.
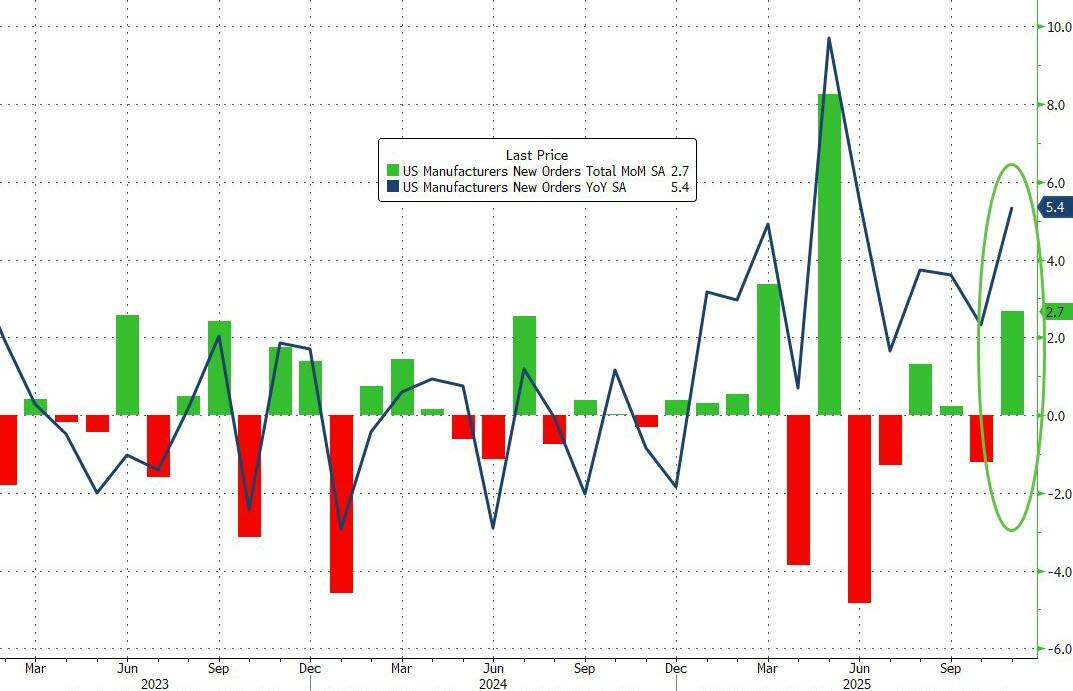
This morning we get a fresh glimpse at America’s manufacturing segment – hard data – with US Factory Orders (admittedly for November) surging 2.7% MoM (significantly better than the +1.6% MoM expected), bouncing strongly from the 1.3% MoM decline in October.
This dragged orders up 5.4% year-over-year…
Source: Bloomberg
This was the biggest monthly advance since May 2025.
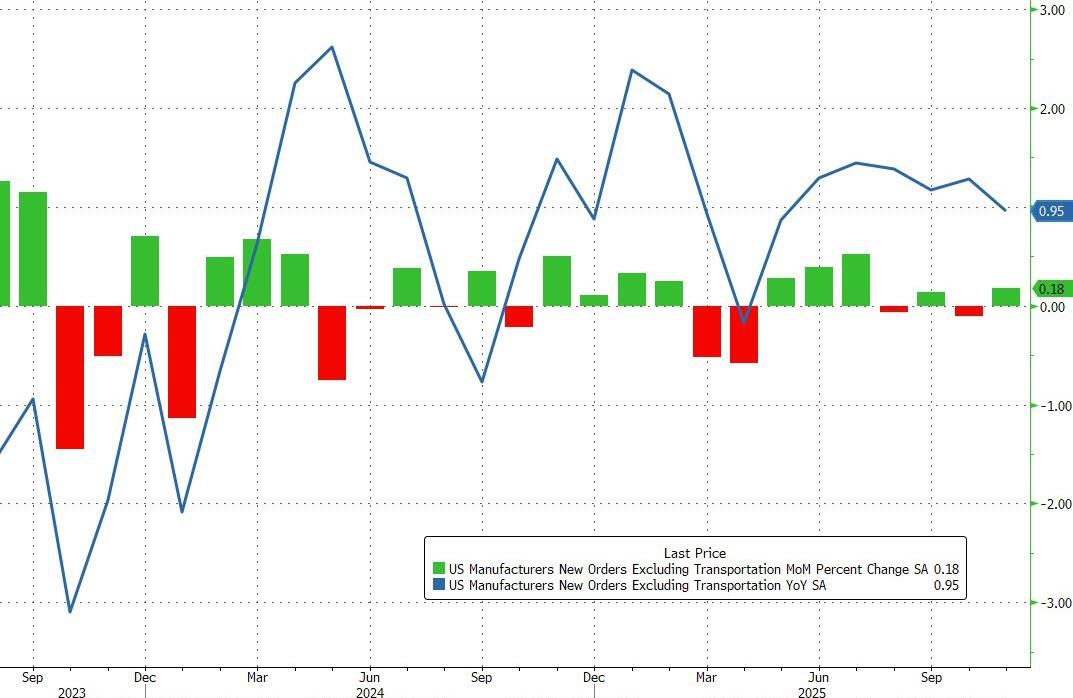
Core Orders (ex transportation) rose 0.2% MoM, also rebounding from a 0.1% MoM decline in October…
Source: Bloomberg
The final print for Durable Goods Orders were all in line with the flash prints.
Of course, this data remains significantly stale (and we face the possibility of another government shutdown to screw things up again), but overall, the trend is your friend (and supported by strong jobless claims data).
https://www.zerohedge.com/economics/us-factory-orders-surged-november
January 25, 2026
Plywood Anti-Dumping Update
Commerce Department rules in favor of preliminary countervailing duties in hardwood plywood cases
By Larry Adams
January 22, 2026 | 8:49 am CST

Prevailing countervailing duties on hardwood plywood imports from China, Indonesia and Vietnam have been calculated.
On January 16, the U.S. Department of Commerce released its preliminary affirmative countervailing duty findings on hardwood and decorative plywood after identifying significant subsidies provided by the governments of China, Indonesia, and Vietnam, reports the Decorative Hardwoods Association.
Commerce calculated preliminary countervailing duties of 81.34% on imports from China, 2.40% to 128.66% on imports from Indonesia, and 4.37% to 26.75% on imports from Vietnam. These rates will be added to existing tariffs on products from these countries and will be charged as soon as the decision is published in the Federal Register.
In addition, preliminary antidumping rates are scheduled to be announced in late February 2026. Final rulings are expected in early May.
The Coalition for Fair Trade in Hardwood Plywood (Coalition), representing a substantial majority of the American hardwood and decorative plywood industry, commends Commerce for its decision to impose these preliminary duties to remedy the unfair trade practices of China, Indonesia, and Vietnam.
“The domestic hardwood and decorative plywood industry has been harmed for decades by unfairly traded imports from China, Indonesia, and Vietnam. Friday’s decision by the Department of Commerce is another critical step in leveling the playing field for American hardwood and decorative plywood manufacturers,” said Timothy C. Brightbill, lead counsel to the Coalition and co-chair of Wiley’s International Trade Practice.
As soon as Commerce’s preliminary determination is published in the Federal Register, U.S. Customs and Border Protection (CBP) will begin collecting preliminary duties on entries of hardwood and decorative plywood from China, Indonesia, and Vietnam. Commerce also found that critical circumstances exist with respect to imports of hardwood and decorative plywood from China. As a result, duties will be collected on entries of hardwood and decorative plywood from China that were entered on or after 90 days before publication of the preliminary determination.
Commerce’s countervailing duty investigations will continue over the coming months, with the agency further investigating subsidies—including newly alleged subsidy programs—received by the Chinese, Indonesian, and Vietnamese industries. Commerce’s final determination is currently scheduled for early May 2026. Commerce is also simultaneously investigating antidumping duty allegations on hardwood and decorative plywood from China, Indonesia, and Vietnam. The preliminary antidumping rates are scheduled to be announced in late February 2026.
The duties that will now be imposed are assessed on the importer of record of the covered merchandise. Duty evasion, absorption, and circumvention are illegal and closely monitored by CBP, in conjunction with the Commerce Department. Counsel for the Coalition is working closely with U.S. Customs and Border Protection to share evidence of duty evasion, which is leading to heightened scrutiny of imports.
January 22, 2026
Automotive Outlook for 2026
2026 Looks Better For US Automakers Than Suppliers; Deutsche Bank
by Tyler Durden
Thursday, Jan 22, 2026 – 03:20 PM
Deutsche Bank is looking at U.S. autos heading into the new year with a growing sense of separation between winners and laggards. In a new 2026 outlook note, Edison Yu and his team argue that while global auto demand remains uneven and suppliers face a tougher volume backdrop, U.S. automakers are entering the year with clearer earnings momentum, helped by better mix, lower EV losses, and a renewed ability to lean into their most profitable internal-combustion vehicles.
At a high level, the bank is cautious on global production growth despite more optimistic industry forecasts. Deutsche Bank sees downside risks tied mainly to China, where changes to government trade-in subsidies are expected to hit lower-priced vehicles hardest. While North America and Europe may improve modestly, the team does not believe those regions can fully offset a potential slowdown in China. As a result, suppliers are likely to guide conservatively for 2026, particularly in the first half of the year, even though fourth-quarter results should generally meet or exceed expectations.

In contrast, the setup for U.S. automakers looks more favorable. Deutsche Bank expects both GM and Ford to deliver solid fourth-quarter results and to grow EBIT by roughly $1–2 billion year over year in 2026. The key driver is not higher unit volumes, but a shift in mix. With regulatory pressure easing, automakers no longer need to restrict production of high-margin trucks and SUVs to meet fleet-wide emissions targets. That flexibility allows them to stock dealerships with more profitable trims, improving margins even if overall sales volumes remain flat or modestly lower.

The pullback from aggressive EV expansion is another important theme. Both Ford and GM have taken multi-billion-dollar write-downs tied to EV programs and battery investments. Deutsche Bank views these moves as painful but necessary resets that reduce future losses, depreciation, and overhead. By clearing out what the bank refers to as “stranded assets,” both companies enter 2026 with a cleaner cost base and a much easier earnings comparison year over year.
For EV-focused companies, the conversation shifts away from near-term vehicle volumes and toward technology execution. Deutsche Bank expects muted underlying volume growth for Tesla and Rivian, with investor attention increasingly centered on autonomy, software, and what the team describes as “physical AI.” For Tesla, that means proving real-world progress in unsupervised full self-driving and robotaxi deployment before earning additional valuation credit. For Rivian, 2026 is framed as a critical year, with the R2 launch needing to demonstrate not just scale, but improving competitiveness in autonomy.

Suppliers face a more complicated picture. China stands out as the biggest wildcard, as revised subsidy rules disproportionately impact lower-priced vehicles and are expected to drive a year-over-year decline in passenger vehicle wholesales. While many global suppliers skew toward higher-end vehicles, which may help mix, Deutsche Bank still expects a net negative volume impact. BorgWarner is singled out as particularly exposed given its historical reliance on China for growth.
Another emerging risk is memory chips. The surge in AI data center demand has pulled wafer capacity away from automotive-grade DRAM, sending prices sharply higher. Deutsche Bank has not yet fully baked a DRAM-driven production hit into its forecasts, but flags it as a meaningful downside risk, especially for suppliers without strong inventory buffers or pricing protections. Some companies, like Aptiv, appear better insulated, while others may feel indirect pressure if vehicle production slows.
Stepping back, Deutsche Bank’s overarching message is that 2026 is shaping up to be less about selling more cars and more about selling the right ones, at the right margins, with tighter cost control. Automakers, particularly in the U.S., appear better positioned to navigate that environment than suppliers. ICE vehicles are once again doing the heavy lifting for profits, EV strategies are being reset to prioritize economics over ambition, and autonomy remains the long-term prize—but one that still requires proof.
https://www.zerohedge.com/markets/deutsche-bank-2026-looks-better-us-automakers-suppliers
January 20, 2026
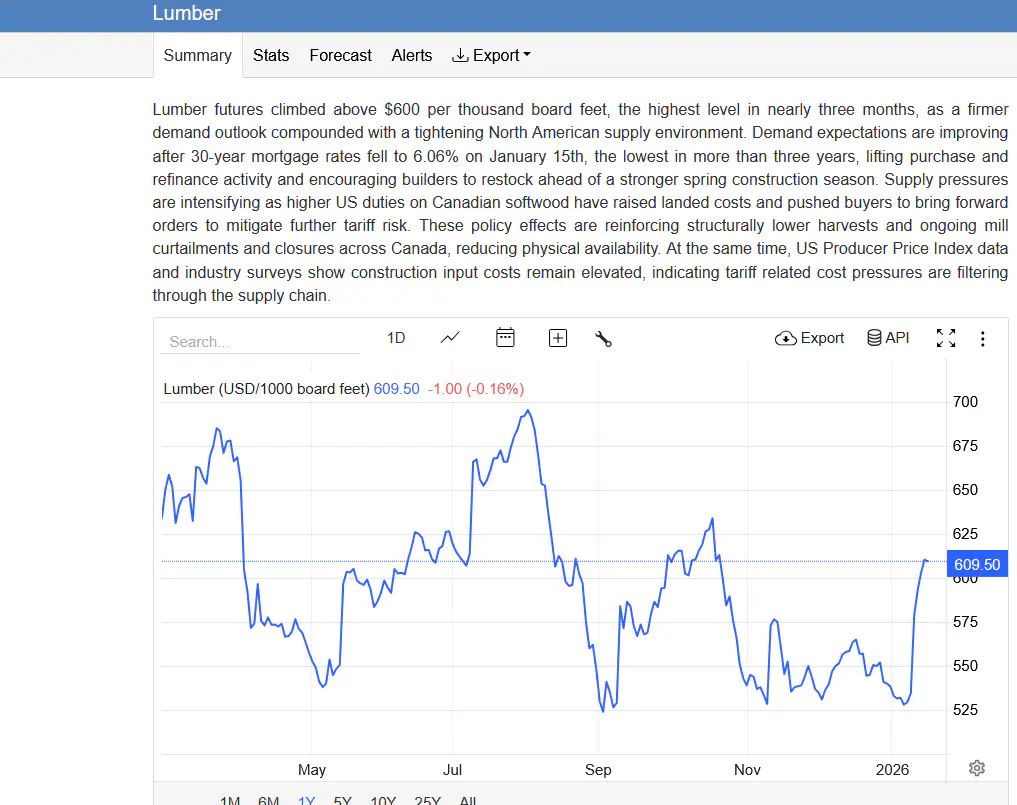
Lumber Prices Rising
 Everchem Updates Archive
 Sign Up for Email Updates


