
The Urethane Blog
May 3, 2026

James David Lewis
January 25, 1963 – April 21, 2026
James David Lewis Obituary
James David Lewis, 63, passed away on April 21, 2026. Born on January 25, 1963, in Falls Church, Virginia. James lived a life defined by strength, love, and an enduring connection to family and the outdoors.
James attended Beloit Memorial High School, where his passion for sports began to take shape. Excelling in football as well as shotput and discus, he carried this dedication with him to the University of Northern Iowa. There, he majored in chemistry on scholarship while playing as a defensive lineman for the university’s football team from 1981 to 1985. The lessons he learned on the field-teamwork and discipline-became guiding principles throughout his life.
James and Laura Lewis (his spouse of 34 years) built a life filled with love and shared memories. He was also a proud father to his daughters Jessica Lewis and Julia Lewis Becker. His family was his greatest joy and priority; he found immense happiness in spending time with them, especially during outdoor adventures like fishing and hunting. These moments were not just hobbies but cherished opportunities to bond and create lasting memories with his daughters.
James is also survived by his sister Angela Victoria Fitzgerald and his nieces and nephews: Matthew Houseman, Michelle Pinkerton, Brendan Fitzgerald, Charity Wielander, Courtney Wielander, Cassy Bowles, and Benjamin Wielander. He was predeceased by his parents, James Edward Lewis and Aurora Peck.
Known for his unshakeable presence and steadfast support for those he loved, James was a rock of stability during life’s challenges. While famously headstrong at times, this trait was always tempered by an unwavering kindness and fierce devotion to his family. He had a unique ability to make those around him feel safe and valued.
A master storyteller with a deep laugh that could light up any room, James had a gift for turning even the simplest memory into an epic tale. His stories often reflected his passions-whether recounting adventures in the woods or sharing humorous anecdotes about football games or coaching experiences.
Later in life, James gave back to his community by coaching shotput and discus for local high schools. His love for competition never waned; it evolved into a desire to mentor young athletes and share the lessons that had shaped him.
When not outdoors or coaching, James enjoyed immersing himself in science fiction worlds like Star Trek and Star Wars. He also had a fondness for Alaskan survival shows and New Glarus beer-especially Spotted Cow-a nod to his Wisconsin roots.
James leaves behind a legacy of warmth, strength, and love that will be deeply missed by all who knew him. May his memory bring comfort to those who mourn his passing while inspiring them to live with the same passion and generosity that defined his life.
A Memorial Service will be held on May 2, 2026, from 12:00 pm until 1:00 pm in the Buford Chapel of Crowell Brothers Funeral Homes & Crematory. There will be a reception held post-service at Julia’s house. Reception will include lunch to continue to celebrate our father’s life. Please message Jessica or Julia for address for reception.
On-line condolences may be expressed at www.crowellbrothers.com. Arrangements entrusted to Crowell Brothers Funeral Homes & Crematory, 201 Morningside Dr., Buford, GA 30518. 770-945-9999.
https://www.crowellbrothers.com/obituaries/James-David-Lewis?obId=48203120
April 30, 2026
Dow Inc. (DOW) Q1 2026 Earnings Call Transcript
Apr 23, 2026, 11:41 AM ETDow Inc. (DOW) Stock
Q1: 2026-04-23 Earnings Summary
EPS of -$0.14 beats by $0.15
| Revenue of $9.79B (-6.11% Y/Y) beats by $124.43M
Dow Inc. (DOW) Q1 2026 Earnings Call April 23, 2026 8:00 AM EDT
Company Participants
Andrew Riker – Vice President of Investor Relations
James Fitterling – Chairman & CEO
Karen Carter – Chief Operating Officer
Jeffrey Tate – Chief Financial Officer
James Fitterling
Chairman & CEO
Thank you, Andrew. I’d like to first take a moment to step back and recognize our colleagues, neighbors, customers and partners in the Middle East who are facing significant turmoil and uncertainty. Our thoughts are with everyone affected by this conflict, and we wish for their safety and well-being during these difficult times.
On Slide 3, I’ll now cover additional details from the first quarter. The solid results we delivered reflect our commitment to controlling what we can control. While January and February order books were solid, we experienced a sharp positive inflection in March with the beginning of the conflict in the Middle East. We expect this supply disruption will persist throughout 2026. During this quarter, we focused on Dow’s strengths of prioritizing our customers, managing costs aggressively and operating with safety, reliability and long-term value creation. We delivered 3% sequential volume growth, net sales of $9.8 billion and operating EBITDA of $873 million. And with our self-help actions well underway, we delivered approximately $193 million in-period cost savings. As we look ahead to the second quarter and beyond, we are taking actions to enhance Dow’s agility and resilience.
We’re also entering a seasonally high demand period, providing additional tailwinds as we move through the next couple of quarters. In addition, an increasingly positive margin backdrop continues to unfold, and we expect the pricing momentum that began in March to continue across every business and every region in Dow’s portfolio.
On the supply side, the conflict in the Middle East has created constraints that are clearly evident in the near term. This includes supply chain disruption for an extended period of time. We also anticipate impact to future investments, including potential delays or cancellations of planned industry capacity additions as well as increased pressure for capacity rationalization. And lastly, we expect that the higher global oil and naphtha prices will steepen the global cost curve.
Against this backdrop, our in-flight actions serve to further strengthen Dow’s competitiveness and position us to drive margin improvement and capture earnings upside. First, our incremental growth investments are delivering returns like our new world-scale polyethylene train in Freeport, Texas. And we’re making progress on our Alberta project, where the overarching merits of this investment in the cost-advantaged Americas are further reinforced by the current global dynamics. In addition, the benefits from our previously announced European asset shutdowns begin this year. And lastly, we are building a Dow that is more agile and resilient through any cycle, a company that delivers through periods of volatility and one that focuses on capturing upside, improving margins and outperforming our peers to effectively reset the competitive benchmark.
We’ll share more details on all of this later in the call, and Karen is going to cover our first quarter operating segment performance. But before that, I’d like to briefly address our recent leadership announcement. Effective July 1, Karen will assume the role of Chief Executive Officer, and I will move to the role of Executive Chair. This announcement follows a deliberate multiyear succession process in partnership with our Board and ensures continuity as we execute our strategy.
Serving as CEO of Dow has been the privilege of a lifetime, and I’m incredibly proud of what our team has accomplished together. This transition comes at the right time as we transform our company for its next phase of growth. I have full confidence in Karen’s leadership, her deep operational experience and her ability to drive performance and value creation. As CEO, she will continue our efforts to transform Dow, positioning us for greater agility and resiliency through any phase of the cycle. She is exactly the right leader to guide our company and deliver on our strategic priorities with discipline and rigor.
Karen Carter
Chief Operating Officer
Thank you, Jim, and good morning to everyone joining today. I’m honored to step into the role of CEO of Dow. Having spent my entire career with the company, I have a deep appreciation for our people, our innovation capabilities and the critical role we play in enabling our customers’ growth. As we look ahead, our priorities remain consistent. We will continue to drive operational excellence, maintain disciplined capital allocation and advance high-value growth in our core markets. Dow is well positioned with our advantaged global portfolio, a strong balance sheet and a talented global team. My focus will be on driving execution, delivering value for our customers and ensuring consistent long-term value for our shareholders. I’m excited about the opportunities ahead and confident in our ability to continue to deliver for all stakeholders.
Turning now to our first quarter results by segment. As Jim mentioned, Team Dow remains focused on disciplined execution in every business throughout the first quarter. As the situation in the Middle East unfolded in March, we continue to manage costs and cash tightly while also prioritizing our customers. We delivered solid results in January and February, and then dynamics in the Middle East quickly impacted industry supply/demand conditions. In fact, our operations outside the region experienced the largest percent sales gain from February to March that we’ve seen in our company’s history.
Our teams remain focused on balancing near-term dynamics with discipline while also progressing our long-term objectives, and this agility continues to be a key differentiator for Dow.
Operating EBIT was $208 million, driven by lower integrated margins and higher planned maintenance activity. This was partly offset by higher polyethylene volumes as well as tailwinds from the company’s cost reduction efforts. Looking ahead, our significant Americas footprint, including our new Poly-7 asset, will enable our teams to capture improved margins.
Next, turning to our Industrial Intermediates & Infrastructure segment on Slide 5. Net sales were $2.6 billion, down 8% year-over-year. This was largely due to lower prices in both businesses as well as lower volumes in Polyurethanes as a result of impacts from the Middle East conflict. Our proactive cost savings actions in both businesses provided tailwinds that offset some of the declines. Volume declined in the quarter as well, primarily due to our actions to reset our competitiveness by shutting down our higher-cost upstream propylene oxide assets late last year. As a reminder, this action rationalized approximately 20% of North American PO industry capacity. And while we are experiencing a prolonged weak demand landscape across building and construction, our new alkoxylation assets are driving growth in Industrial Solutions, which serves attractive end markets such as home care, pharma and energy.
Next, on Slide 7, I’ll take a step back to frame further details on the current macroeconomic environment. The headline is this. Demand across many markets is steady. At the same time, supply is short and arbitrage is increasing. On the demand side, for our core polyethylene packaging markets, conditions remain resilient, but we are seeing mixed signals in other key markets that Dow serves. For example, in the U.S., inflationary pressures and higher interest rates are still weighing on existing home sales. This continues to be reflected in our Industrial Intermediates & Infrastructure and Performance Materials & Coatings segments, both of which serve the building and construction market. Consumer spending has shown some modest improvement, but the landscape and behaviors are likely to remain cautious until we see a significant inflection in macroeconomic conditions.
Moving to supply dynamics. We anticipate that shutdowns, feedstock limitations and logistical constraints will continue to reshape polyethylene product availability across regions. These conditions are creating ripple effects well beyond the Middle East, including significant impacts to logistics costs and transit times. Supply and feedstocks into Asia and Europe are constrained, which is triggering price increases globally. It is also leading to increased production in the Americas and is providing Dow the opportunity to capture new business in Europe. The duration and severity of these constraints increases the likelihood of lasting industry impacts, including the potential for accelerated capacity rationalization as well as delays or cancellation of planned capacity additions.
In this context, expectations for higher U.S. supply are helping to ease some of the pressure and provide stability. North American LNG markets remain well supplied and regionally insulated from these disruptions. In addition, U.S. Gulf Coast NGLs, including ethane, continue to be largely unimpacted. All of these factors underscore the benefits of Dow’s cost advantaged footprint in the Americas.
Next on Slide 8, we’ll unpack some of the current regional and industry impacts in more detail. In the 2 months since the conflict began, the scale of disruption we have seen is unprecedented. Roughly 20% of global oil capacity is currently offline and approximately half of global ethylene and polyethylene supply is either offline, constrained or directly impacted. These are unparalleled numbers, reflecting a combination of physical infrastructure damage, feedstock limitations and severe logistics disruptions.
Transit through the region remains significantly impaired, largely driven by the ongoing disruption in the Strait of Hormuz, and the disruption has been amplified across Asia and Europe, tightening feedstock availability and pushing producers to reduce production or increase prices to cover the rapidly escalating costs occurring from the conflict. Looking across regions, a large portion of Middle East capacity remains offline with increasing risk of lasting infrastructure damage. In Asia Pacific, feedstock constraints are limiting operating rates and reducing export availability, challenging producers who are operating at uncompetitive levels. And in Europe, high costs will require continued price increases to justify additional production. In contrast, the Americas continue to operate at high rates, highlighting the importance of Dow’s cost and feedstock advantages in the region.
Currently, it is estimated that roughly 3/4 of announced global capacity additions would be either directly impacted by the conflict or dependent on supply chains that remain highly constrained. The longer these conditions persist, the greater the potential for further industry changes. And lastly, it is not likely that the pricing impact of these events will be temporary. We expect rising global production costs and a steepening global cost curve to continue influencing pricing and spreads.
Next, I’ll turn to Slide 9, where we will discuss how Dow’s specific advantages drive near-term value. At the beginning of the Middle East conflict, petrochemical prices, especially polyethylene, were at multiyear unsustainable lows. Despite broader near-term market volatility, we anticipate packaging demand will remain resilient, providing meaningful pricing potential as evidenced by recent March settlements. That brings me to our advantaged global asset footprint.
Dow operates a large portion of our light cracking capacity in the cost advantaged Americas with assets in the U.S., Canada and Argentina, all of which continue to operate at high rates. Our consistent focus on investing in the Americas gives us reliability, feedstock security and cost stability at a time when global supply chains are strained. In Europe, our feedstock flexibility remains a critical differentiator. With naphtha supplies impaired and Pro-Nap spreads increasing, Dow’s ability to optimize across feedstocks provides a clear cost and availability advantage versus peers. This allows us to protect and expand margins through running our assets competitively even in a volatile energy and feedstock environment. And specific to our Packaging & Specialty Plastics segment, Dow has higher North American capacity than our closest peer, further supported by the 2025 start-up of our Poly-7 polyethylene train in Freeport, Texas.
Additionally, in the first quarter, we announced a series of senior leadership changes that delivered an approximately 20% reduction in both headcount and cost at that level. We remain confident that our collective efforts in Transform to Outperform will ramp sharply to $400 million in the second half of the year, creating a Dow that is more resilient across the cycle while consistently delivering growth, customer success and improved shareholder value. And as an important reminder, all of our self-help actions and the upside they provide are additive to the potential upside we anticipate going into the second quarter.
James Fitterling
Chairman & CEO
Thank you, Jeff. As I look at Slide 13, it really captures how we position Dow, not just for this quarter or this year, but for long-term value creation through the cycle. First, even in a disrupted industry environment, we are well positioned to navigate market dynamics, which was apparent in our first quarter results. Our order books were solid in January and February, and we saw a sharp positive inflection in March, and we expect that to continue throughout 2026. As a result, the positive momentum from announced pricing actions across every business and every region is taking hold and building.
Patrick Cunningham
Citigroup Inc., Research Division
Could you perhaps walk through any impact of the conflict on maybe the 10% to 15% of non-polyolefin derivatives that are exposed to some of these tightening market dynamics and where you might see the biggest potential for additional export opportunities or advantaged footprint taking advantage of some of the higher margins?
James Fitterling
Chairman & CEO
Well, ethylene, polyethylene, ethylene glycol has probably been the biggest impact of all of it. And so you see that already showing up in the market response and what’s happening. And those should be able to repair quickly. That’s also one of the things you see in the results with EQUATE’s earnings in the first quarter was, remember, EQUATE has operations in Canada and Texas. And so they have a global footprint on MEG. So they’re able to supply their customers and also take advantage of the price increases and that more than offsets the situation that they have to deal with locally. But they’ll be able to get that back up and moving once the roadblock clears.
I would say on propylene derivatives, there are some — obviously, we have some in the polyurethanes business that will be impacted. There’s some polypropylene that will be impacted. I think in Polypro, you had a little bit different situation in downstream, demand dynamics, auto being slow, appliances being slow, [indiscernible] takes a little demand pressure off of Polypro. So we haven’t seen the same kind of dynamics there. MDI similar. Other things you want to bring in, Karen?
April 30, 2026
Home building shows signs of stabilization with March starts
By Dakota Smith
April 29, 2026 | 8:49 am CDT
WASHINGTON, D.C. — Housing production bounced back in March as builders cautiously ramp up production despite ongoing headwinds.
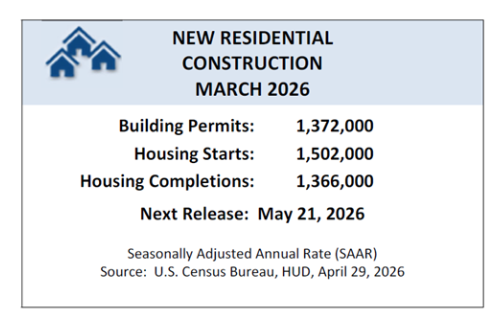
The March reading of 1.5 million starts is the number of housing units builders would begin if development kept this pace for the next 12 months. Within this overall number, single-family starts increased 9.7% to a 1.03 million seasonally adjusted annual rate and are up 8.9% compared to March 2025. The multifamily sector, which includes apartment buildings and condos, increased 13.3% to an annualized 470,000 pace and are up 15.5% compared to March 2025.
“Housing starts posted a solid rebound in March, suggesting builders are responding to pockets of improving demand despite ongoing affordability challenges, although activity remains sensitive to interest rate movements and construction costs,” said Bill Owens, chairman of the National Association of Home Builders (NAHB) and a home builder and remodeler from Worthington, Ohio. “Overall, the uptick in housing starts is a positive development for residential investment and signals that the sector may be stabilizing.”
“Single-family starts drove much of the monthly increase, indicating that builders are cautiously ramping up production to meet persistent inventory shortages in the resale market,” said Danushka Nanayakkara-Skillington, NAHB’s assistant vice president for forecasting and analysis. “While this is an encouraging sign, the pace of construction is likely to remain measured as builders continue to navigate elevated financing costs and labor availability. On a regional level, the Midwest continues to outshine the rest of county as the only region to have positive single-family starts growth.”
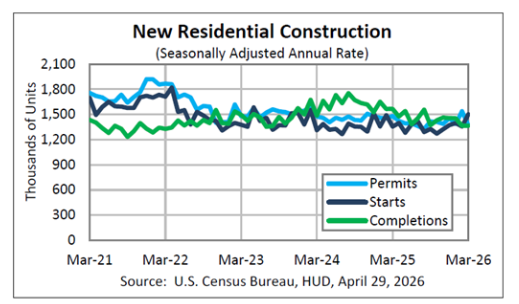
Overall permits decreased 10.8% to a 1.37 million unit annualized rate in March. Single-family permits decreased 3.8% to an 895,000-unit rate and are down 7.9% compared to March 2025. Multifamily permits decreased 21.5% to an annualized 477,000 pace and are down 6.3% compared to March 2025.
Looking at regional permit data on a year-to-date basis, permits were 15.4% higher in the Northeast, 1.1% higher in the Midwest, 9.1% lower in the South and 6% higher in the West.
The number of single-family homes under construction is at 587,000 units while the number of apartments under construction is at 677,000 units.
April 23, 2026
Dow tops estimates as cost cuts help to narrow quarterly loss
Apr 23, 2026, 7:11 AM ETDow Inc. (DOW) StockBy: Rob Williams, SA News Editor
Dow Inc. (DOW), one of the world’s largest chemicals and materials manufacturers, reported first-quarter results on Thursday that beat Wall Street expectations for both revenue and adjusted earnings despite posting a net loss.
Shares of Dow (DOW) rose 1.8% in premarket trading. As of Wednesday’s close, the stock was up 34% over the prior 12 months.
Net sales fell 6% to $9.79 billion from $10.43 billion a year earlier, but still topped analysts’ consensus estimate of $9.67 billion. Operating earnings per share, the company’s adjusted measure, showed a loss of $0.14 a share, better than the expected adjusted loss of $0.29 a share.
Net income fell to a loss of $445 million, or $0.74 a share, from a loss of $290 million, or $0.44 a share, a year earlier.
Cost cuts help offset weak pricing
Dow (DOW) said lower prices and softer demand weighed on results, though benefits from its cost reduction efforts helped cushion the impact.
“In the first quarter, our results reflect the growing impact of Dow’s self-help actions,” Chief Executive Jim Fitterling said in the earnings release.
Volume declined 2% year over year, while local prices fell 7%. Gains in packaging plastics volumes were offset by lower sales in industrial intermediates and infrastructure products, partly tied to conflict-related disruptions in the Middle East.
Packaging business leads segments
Dow’s (DOW) Packaging & Specialty Plastics unit, its largest segment, generated $4.9 billion in revenue, down 7% from a year earlier. Performance Materials & Coatings sales were roughly flat at $2.08 billion, while Industrial Intermediates & Infrastructure revenue declined 8% to $2.63 billion.
The coatings and silicones businesses benefited from stronger demand tied to electronics, home and personal care applications.
Cash flow improves, outlook firms
Dow (DOW) reported earnings before interest, taxes, depreciation and amortization of $873 million, compared with $944 million a year earlier. Cash provided by operating activities from continuing operations jumped to $1.12 billion from $104 million a year earlier.
Fitterling said pricing actions across businesses and regions were already creating momentum, while the company’s manufacturing footprint and supply chain flexibility positioned it for improved growth, wider margins and stronger shareholder returns.
Dow (DOW) makes plastics, industrial chemicals, coatings materials and silicones used in packaging, construction, automotive, electronics and consumer products. Its well-known brands include Styrofoam insulation, Silastic silicone materials and Dowlex polyethylene resins used in flexible packaging.
April 23, 2026

Americanstar expands Mattress King lineup to 13 SKUs
Sheila Long O’Mara //Executive Editor, Furniture Today//April 20, 2026
WACO, Texas — Americanstar Mattress is expanding its retail footprint in the Midwest through a deeper partnership with Oklahoma-based Mattress King, underscoring continued momentum for the Texas manufacturer’s premium, margin-focused assortment.
Mattress King, which operates six sleep specialty stores across Oklahoma, has increased its Americanstar lineup to 13 SKUs across all of the retailer’s locations. The retailer said Americanstar’s Presidential hybrid collection has been its retailer’s top-selling mattress line for four consecutive years.
Ryan Farris, CEO of Mattress King, said the decision to expand the assortment was driven by both consumer demand and ease of selling on the showroom floor.
“Americanstar has proven to be a strong partner for our business,” Farris said. “Their products resonate with our customers, and just as importantly, they give our sales team a compelling story that’s easy to tell. When your top best-sellers all come from one vendor, expanding that relationship isn’t a question; it’s the obvious next step.”
The expanded assortment brings a broader range of price points and constructions to Mattress King’s floors, including Americanstar’s S-Class, Cleopatra, First Class, Presidential, Medispa Prestige, Ecoflex and Capella collections. Company officials said the lineup is designed to give retail sales associates flexibility in addressing varying comfort preferences while maintaining the margin structure that has supported strong sell-through.
Tony Nguyen, chief operating officer of Americanstar U.S., said the partnership reflects the company’s strategy of aligning with retailers focused on performance at the store level.
“Mattress King is exactly the kind of retail partner we’re proud to grow with,” Nguyen said. “They understand what drives results on the floor and have built their business around delivering real value to their customers. When performance validates the partnership this clearly, it reinforces our focus on supporting retailers with products that are consistent, reliable and profitable.”
The Oklahoma expansion comes as Americanstar continues to scale its presence across North America. In recent months, the company has broadened its relationship with Texas-based Bel Furniture, more than doubling its in-store presence, expanded with Mattress Firm Montana, and entered Kansas through a statewide rollout with The Mattress Hub.
Supporting that growth is an increased investment in domestic manufacturing. Americanstar’s 200,000-square-foot facility in Waco now includes in-house foam production, leveraging more than two decades of global foam-pouring expertise. The vertical integration allows the company to develop proprietary materials, including its SilkFoam technology, while maintaining cost efficiencies aimed at supporting retailer margins.
Company officials said the combination of product performance, manufacturing control and retail alignment continues to position Americanstar for further expansion as it builds out its U.S. distribution network.
 Everchem Updates Archive
 Sign Up for Email Updates