
The Urethane Blog
September 29, 2021
China economy to slow as industries struggle from power crunch
Author: Fanny Zhang
2021/09/29
SINGAPORE (ICIS)–China’s economic prospects are being weighed down by an ongoing power crunch in a huge swathe of the country, threatening overall industrial production, with much tighter controls on energy consumption in place in selected provinces in September.
Some investment banks have shaved their GDP growth forecast for the second-biggest economy below 8% as industries struggle from power shortage stemming from high coal prices, and efforts by some provinces to keep within their respective energy consumption targets in the third quarter.
Goldman Sachs now expects China to post a 7.8% GDP growth in 2021, down from its previous forecast of 8.2%.
The US investment bank cited “significant downside pressures” from major industrial output cuts caused by power outages, which affect an estimated 44% of the country’s industrial activity.
China-based investment bank China International Capital Corp (CICC) expects the GDP drag would be 0.1-0.15 percentage point in both the third and fourth quarters, with overall industrial output to be reduced by 1.3%-1.5%.
A prolonged production cut could shave China’s fourth-quarter GDP growth by a full percentage point, according to US-based investment bank Morgan Stanley.
Japan-based Nomura has likewise revised down its full-year GDP forecast for China to 7.7% from 8.2% previously, with third-quarter and fourth-quarter growths projected to come in at 4.7% and 3%, respectively.
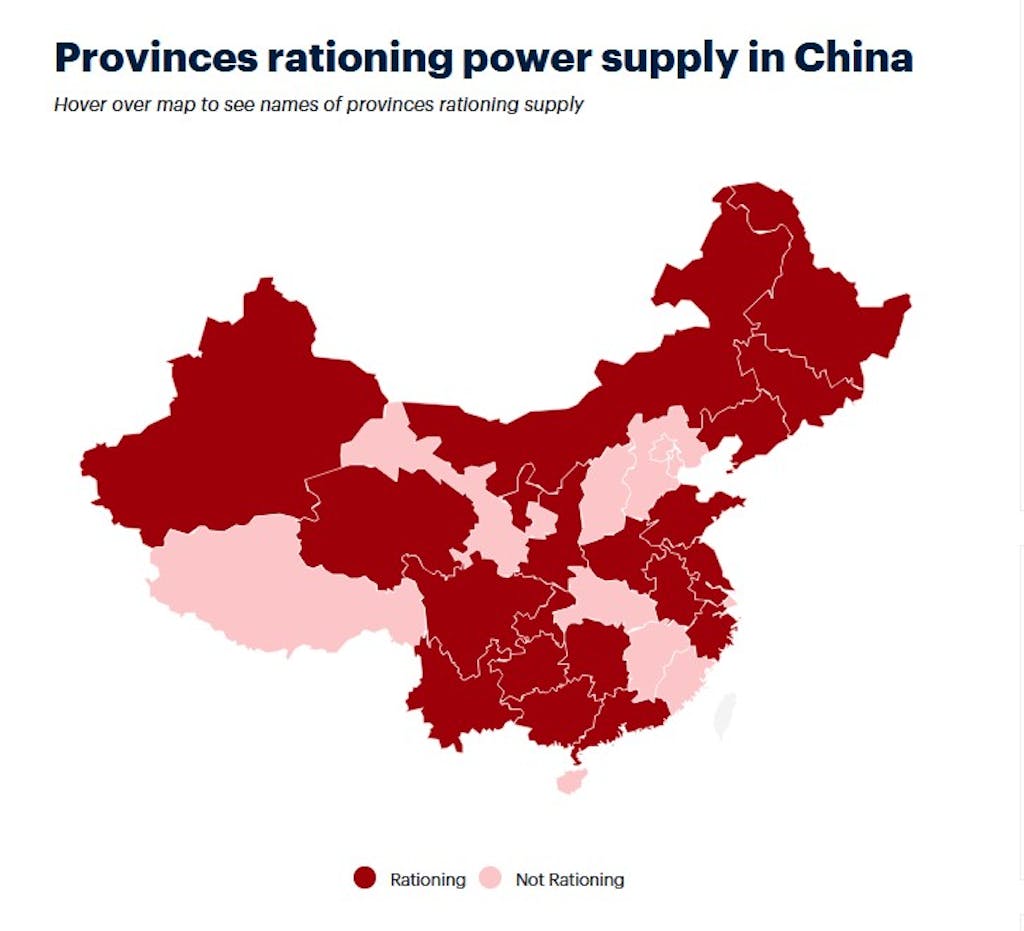
Power rationing is now in place at 20 of the 31 provinces/municipalities in mainland China, with coal-based power plants running at reduced rates to stem losses arising from high feedstock costs. https://e.infogram.com/5e89a67b-46d1-4592-9a81-1604a5610c85?parent_url=https%3A%2F%2Fwww.icis.com%2Fexplore%2Fresources%2Fnews%2F2021%2F09%2F29%2F10689696%2Fchina-economy-to-slow-as-industries-struggle-from-power-crunch&src=embed#async_embed
China has been leading the global economic rebound from a pandemic-driven slump in 2020, having successfully contained COVID-19 infections much earlier than the rest of the world.
Its industries have been working double time to accommodate increased export orders, thereby causing unprecedented spikes in energy consumption.
But the country also has a commitment to reduce carbon emissions, with specific annual targets on energy consumption set for each province, in line with the goal of achieving net-zero emissions by 2060, based on China’s 14th Five-Year Plan.
In September, some provinces well in excess of the limits on total energy consumption as well as intensity (consumption per GDP) in the first half of 2021 have moved to rectify the issue, aggravating the effects of the power shortage and hitting downstream industries hard.
Factories are being forced to cut production or shut operations, and in some regions, office buildings, shopping centres and even residential homes are affected.
Power companies are losing money from high cost of coal, said freelance economist Guan Qingyou.
Spot prices of coal – which accounts for 70% of China’s total power generation – nearly quadrupled from 2020 levels to $180/tonne, in line with strong gains in global commodity prices this year.
China’s energy challenges may not be resolved in the short term, Guan said.
Industrial production in China has weakened for five straight months, with the August official purchasing managers index (PMI) reading of 50.1 barely above the threshold for expansion.
Another concern looming in the background for the Chinese economy is the debt-saddled giant property developer Evergrande.
The company, which is China’s second-bigger property developer, has accumulated $305bn in debt, which was about 2% of China’s GDP.
Analysts said that Evergrande’s collapse is threatening stability of the Chinese property market, as well as financial system.
Focus article by Fanny Zhang
September 29, 2021
China economy to slow as industries struggle from power crunch
Author: Fanny Zhang
2021/09/29
SINGAPORE (ICIS)–China’s economic prospects are being weighed down by an ongoing power crunch in a huge swathe of the country, threatening overall industrial production, with much tighter controls on energy consumption in place in selected provinces in September.
Some investment banks have shaved their GDP growth forecast for the second-biggest economy below 8% as industries struggle from power shortage stemming from high coal prices, and efforts by some provinces to keep within their respective energy consumption targets in the third quarter.
Goldman Sachs now expects China to post a 7.8% GDP growth in 2021, down from its previous forecast of 8.2%.
The US investment bank cited “significant downside pressures” from major industrial output cuts caused by power outages, which affect an estimated 44% of the country’s industrial activity.
China-based investment bank China International Capital Corp (CICC) expects the GDP drag would be 0.1-0.15 percentage point in both the third and fourth quarters, with overall industrial output to be reduced by 1.3%-1.5%.
A prolonged production cut could shave China’s fourth-quarter GDP growth by a full percentage point, according to US-based investment bank Morgan Stanley.
Japan-based Nomura has likewise revised down its full-year GDP forecast for China to 7.7% from 8.2% previously, with third-quarter and fourth-quarter growths projected to come in at 4.7% and 3%, respectively.
Power rationing is now in place at 20 of the 31 provinces/municipalities in mainland China, with coal-based power plants running at reduced rates to stem losses arising from high feedstock costs. https://e.infogram.com/5e89a67b-46d1-4592-9a81-1604a5610c85?parent_url=https%3A%2F%2Fwww.icis.com%2Fexplore%2Fresources%2Fnews%2F2021%2F09%2F29%2F10689696%2Fchina-economy-to-slow-as-industries-struggle-from-power-crunch&src=embed#async_embed
China has been leading the global economic rebound from a pandemic-driven slump in 2020, having successfully contained COVID-19 infections much earlier than the rest of the world.
Its industries have been working double time to accommodate increased export orders, thereby causing unprecedented spikes in energy consumption.
But the country also has a commitment to reduce carbon emissions, with specific annual targets on energy consumption set for each province, in line with the goal of achieving net-zero emissions by 2060, based on China’s 14th Five-Year Plan.
In September, some provinces well in excess of the limits on total energy consumption as well as intensity (consumption per GDP) in the first half of 2021 have moved to rectify the issue, aggravating the effects of the power shortage and hitting downstream industries hard.
Factories are being forced to cut production or shut operations, and in some regions, office buildings, shopping centres and even residential homes are affected.
Power companies are losing money from high cost of coal, said freelance economist Guan Qingyou.
Spot prices of coal – which accounts for 70% of China’s total power generation – nearly quadrupled from 2020 levels to $180/tonne, in line with strong gains in global commodity prices this year.
China’s energy challenges may not be resolved in the short term, Guan said.
Industrial production in China has weakened for five straight months, with the August official purchasing managers index (PMI) reading of 50.1 barely above the threshold for expansion.
Another concern looming in the background for the Chinese economy is the debt-saddled giant property developer Evergrande.
The company, which is China’s second-bigger property developer, has accumulated $305bn in debt, which was about 2% of China’s GDP.
Analysts said that Evergrande’s collapse is threatening stability of the Chinese property market, as well as financial system.
Focus article by Fanny Zhang
September 28, 2021
Why Is The Number Of Railcars In Storage Important?
by Tyler DurdenTuesday, Sep 28, 2021 – 02:10 PM
By Joanna Marsh of FreightWaves,
Rail equipment manufacturers, suppliers and industry observers will talk about the number of railcars in storage being up or down. But why is that figure important?
Knowing how many railcars are in storage is significant because that figure helps observers understand network capacity in relation to the broader economy. Industry participants also look at the number of railcars in storage by railcar type to gauge expectations for where railcar lease rates are heading and the volume of orders that manufacturers will receive for newly built railcars.
A number of organizations, such as the advocacy group Railway Supply Institute and the data firm Commtrex, keep track of how many railcars are in storage, including what type of railcar as different railcars can haul different commodities. The kinds of railcars that may be stored can range from pool fleets and auto racks to coal cars and tank cars.
One reason why there are so many railcars in storage is that railcars are very specific to the type of freight being moved. There are often shortages of some railcar types and surpluses of other railcar types at the same time.
For instance, if more grain needs to be shipped domestically and for export, then more hopper cars will be needed to move that grain. If there is less grain to be shipped, then railcar owners may store some of those hopper cars temporarily.
Sometimes a commodity will see volumes facing a systemic decline and that will be reflected in the type of railcars in storage. Sand used in the natural gas fracking process was transported in small cube covered hoppers. But when companies began using local sand instead of shipping sand via rail, that lessened the number of small cube covered hoppers on the rail network — and increased the number of those railcars in storage.
Also, when natural gas began to displace coal as the primary feedstock to generate electricity, coal volumes fell, sending coal cars into storage.
“As demand goes down, some of those cars go into storage and that drives the number of cars in storage,” said Lee Verhey, director of regulatory and industry affairs for the Railway Supply Institute.
The broader economy can influence how many railcars are in storage. When the COVID-19 pandemic first hit in the spring of 2020, manufacturing rates and in-store consumer activity took a nosedive amid social distancing measures. As a result, U.S. rail volumes sank in April and May 2020. Because there was less rail traffic, more railcars went into storage.
“The market really drives the availability of cars,” Verhey said.
“As demand [to haul certain commodities] goes down, some of those cars go into storage and that drives the number of cars in storage.”
The number of railcars in storage was as high as more than 525,000 cars in July and August 2020, a manager with railcar manufacturer Greenbrier said recently. That number has been steadily declining over the last 14 months to below 400,000, which is more in line with normal levels.
“As the economy starts to gain momentum and we start to see manufacturing starting to increase and supply starting to be more available, then you have greater demand for cars,” Verhey said.
A portion of the railcars in storage are older and less efficient than newer railcars because they have lower payload-to-weight ratios. Therefore, some of the railcars in storage may never come back into service.
Railcar leasing companies own roughly 70% of the U.S. fleet, while freight railroads own about 30%. A customer, such as a chemical company, will need railcars to move product, and that customer will get quotes from the railcar lessors for rates. The leases may be short term or long term.
Meanwhile, the railroads tend to own boxcars or railcars to haul grain or agricultural products. The company TTX is a joint venture owned by the railroads that serves as a railcar pool. But the railroads don’t own tank cars, which have their own special regulations for handling.
Lastly, a handful of companies will own their railcars, such as Exxon Mobil, Shell and ConocoPhillips. The decision to own railcars depends on the company’s financial strategy, according to Verhey. Some may lease cars because they don’t want to invest in the cars, but some might find it financially advantageous to own their railcars if they serve a niche market.
https://www.zerohedge.com/economics/why-number-railcars-storage-important
September 28, 2021
Why Is The Number Of Railcars In Storage Important?
by Tyler DurdenTuesday, Sep 28, 2021 – 02:10 PM
By Joanna Marsh of FreightWaves,
Rail equipment manufacturers, suppliers and industry observers will talk about the number of railcars in storage being up or down. But why is that figure important?
Knowing how many railcars are in storage is significant because that figure helps observers understand network capacity in relation to the broader economy. Industry participants also look at the number of railcars in storage by railcar type to gauge expectations for where railcar lease rates are heading and the volume of orders that manufacturers will receive for newly built railcars.
A number of organizations, such as the advocacy group Railway Supply Institute and the data firm Commtrex, keep track of how many railcars are in storage, including what type of railcar as different railcars can haul different commodities. The kinds of railcars that may be stored can range from pool fleets and auto racks to coal cars and tank cars.
One reason why there are so many railcars in storage is that railcars are very specific to the type of freight being moved. There are often shortages of some railcar types and surpluses of other railcar types at the same time.
For instance, if more grain needs to be shipped domestically and for export, then more hopper cars will be needed to move that grain. If there is less grain to be shipped, then railcar owners may store some of those hopper cars temporarily.
Sometimes a commodity will see volumes facing a systemic decline and that will be reflected in the type of railcars in storage. Sand used in the natural gas fracking process was transported in small cube covered hoppers. But when companies began using local sand instead of shipping sand via rail, that lessened the number of small cube covered hoppers on the rail network — and increased the number of those railcars in storage.
Also, when natural gas began to displace coal as the primary feedstock to generate electricity, coal volumes fell, sending coal cars into storage.
“As demand goes down, some of those cars go into storage and that drives the number of cars in storage,” said Lee Verhey, director of regulatory and industry affairs for the Railway Supply Institute.
The broader economy can influence how many railcars are in storage. When the COVID-19 pandemic first hit in the spring of 2020, manufacturing rates and in-store consumer activity took a nosedive amid social distancing measures. As a result, U.S. rail volumes sank in April and May 2020. Because there was less rail traffic, more railcars went into storage.
“The market really drives the availability of cars,” Verhey said.
“As demand [to haul certain commodities] goes down, some of those cars go into storage and that drives the number of cars in storage.”
The number of railcars in storage was as high as more than 525,000 cars in July and August 2020, a manager with railcar manufacturer Greenbrier said recently. That number has been steadily declining over the last 14 months to below 400,000, which is more in line with normal levels.
“As the economy starts to gain momentum and we start to see manufacturing starting to increase and supply starting to be more available, then you have greater demand for cars,” Verhey said.
A portion of the railcars in storage are older and less efficient than newer railcars because they have lower payload-to-weight ratios. Therefore, some of the railcars in storage may never come back into service.
Railcar leasing companies own roughly 70% of the U.S. fleet, while freight railroads own about 30%. A customer, such as a chemical company, will need railcars to move product, and that customer will get quotes from the railcar lessors for rates. The leases may be short term or long term.
Meanwhile, the railroads tend to own boxcars or railcars to haul grain or agricultural products. The company TTX is a joint venture owned by the railroads that serves as a railcar pool. But the railroads don’t own tank cars, which have their own special regulations for handling.
Lastly, a handful of companies will own their railcars, such as Exxon Mobil, Shell and ConocoPhillips. The decision to own railcars depends on the company’s financial strategy, according to Verhey. Some may lease cars because they don’t want to invest in the cars, but some might find it financially advantageous to own their railcars if they serve a niche market.
https://www.zerohedge.com/economics/why-number-railcars-storage-important
September 28, 2021
Higher costs drive re-examination of Covestro MDI plant location plans – CEO
Author: Tom Brown
2021/09/28
LONDON (ICIS)–A significant increase in construction costs in the US has become a factor in Covestro moving to re-examine the potential location of its planned flagship methylene diphenyl diisocyanate (MDI) plant, with China mooted as an alternative.
The company announced on Tuesday that it intends to proceed with work on a world-scale MDI plant, after suspending plans to build a unit in the US in early 2020.
The producer had announced in January 2020 that it would halt work on its planned 500,000 tonne/year MDI plant at its Baytown, Texas, production complex, in the face of challenging global market conditions.
A substantial increase in construction costs in the US, both in terms of labour and materials, since the project was first announced in 2018 could result in a lower return on capital employed (ROCE) than originally anticipated, prompting the re-examination of the location for the investment.
“Construction costs in the US have significantly increased, leading to a lower return on capital employed versus our original plan,” said Covestro CEO Markus Steilemann, speaking on an investor call.
“In China, construction costs have remained relatively flat, with attractive ROCE. Strong demand growth in China and Asia creates the need for another plant in Asia,” he added.
The company targets a return of at least seven percentage points above its cost of capital, according to CFO Thomas Toepfer, meaning a target ROCE of around 15%.
“That is certainly a challenge for a greenfield investment. But we think that we will be at least close to that, and therefore, this is also why we’re critically looking into all the options with respect to locations,” he said.
The company’s existing MDI assets are fully utilised at present, according to Steilemann, with a project to increase capacity at its Tarragona, Spain, plant, still underway but expected by 2025 instead of the initial estimate of 2022 when the project was first announced at the end of 2017.
“We are only able to grow below demand growth until the start-up of a new plant,” he said.
Covestro had originally guided for capital expenditure of $1.5bn for its new world-scale plant, but that figure may be set to rise irrespective of its final location in China or the US.
“I would say it’s not a secret that there has been significant cost inflation since [the project was announced], especially for materials like steel but also for labour, especially in the US, so this is one of the reasons why we are looking into all the options we have,” Steilemann said.
“Relative to the $1.5bn, there would be a slight increase to that in China, but there would certainly be a significant increase in the US,” he added.
A decision will be announced at the next stage of project development, he added, with the plant expected to be commissioned in 2026, two years after the original forecast start date for the Baytown project. The plant capacity is also likely to be around the originally forecast 500,000 tonnes/year, but the final figure is still to be determined.
OTHER INVESTMENTS
The firm is also planning to expand its toluene diisocyanate (TDI) production by de-bottlenecking facilities in Dormagen, Germany, expected to be complete by 2023. The unit currently has a production capacity of 250,000 tonnes/year, according to ICIS data.
Also earmarked for investment are coatings and adhesives, and specialty films, with planned expenditure of €300m and €200m apiece by 2025, while the firm is planning more investment in the circular economy.
“In order to achieve our ambitious objectives and become fully circular, we are planning targeted capex spending of around €1bn on circular economy projects over the next ten years,” Toepfer said.
Covestro is planning to increase capital spending over the next few years, with an estimated €800m of investment this year expected to expand substantially in the near future, he added.
On the back of new investments, the realignment of the business into solutions and specialties and performance materials in mid-2021, and the acquisition of DSM’s resins and functional materials business, Covestro expects to increase mid-cycle earnings before interest, taxes, depreciation and amortisation (EBITDA) from €2.2bn to €2.8bn by 2024, the company added.
(update re-leads, adds CEO, CFO comment)
 Everchem Updates Archive
 Sign Up for Email Updates