
Asian Markets
February 26, 2025
Bismuth Catalyst Disruption Ahead
China Announces Export Controls on Five Critical Minerals
Proactive intelligence Alert
February 12, 2025
On February 4, 2025, China announced it would restrict exports of five critical minerals: tungsten, tellurium, bismuth, indium, and molybdenum. Industries dependent on these metals, including defense, renewable energy, electronics, and manufacturing, may experience supply chain disruptions, including delays, price increases, and supply bottlenecks, due to China’s leading role in their production.
 | Tungsten | Artillery shells, armor plating, cutting tools, engine parts, airplane balancing weights. |
 | Tellurium | Solar panels, thermoelectric devices, infrared optics, steel alloys, and rechargeable batteries. |
 | Bismuth | Medical treatments, lead-free solder, cosmetics, flame retardants, and ammunition. |
 | Indium | Phone screens, TV displays, fiber-optic technology, semiconductors, and solar panels. |
 | Molybdenum | Missile components, nuclear reactors, steel alloys, lubricants, and high-temperature electronics. |
Background
China’s new export controls require licenses to export 20 tungsten, tellurium, bismuth, indium and molybdenum-related products to “safeguard national security interests.” China is the global leader of the rare earths industry overall, dominating about 69% of the world’s production and 90% of the world’s mining. China is the top producer of all five recently restricted metals.
China’s Production of Impacted Minerals

Source: Bloomberg
In recent years, China restricted the exports of several other critical minerals. In July 2023, China announced export restrictions on certain gallium and germanium products, metals essential in chip manufacturing, citing national security concerns. Following the announcement, prices for gallium and germanium surged, with gallium prices increasing by nearly 20% in the United States and Europe.
In August 2024, China announced restrictions on antimony, a metal used in defense technology. From August 2024 to December 2024, antimony shipments from China to the United States dropped 97% while prices rose 200%. In December 2024, China banned the export of gallium, germanium, and antimony to the United States entirely.
The scope of China’s export restrictions on the five minerals also includes a ban on the technology to process and refine the materials for their critical uses. This factor pressures rival economies to develop independent supply chains and creates short-term bottlenecks that could disrupt industries relying on these materials.
Exiger Insights
Although China’s recent restrictions do not single out exports to any particular country, the announcement followed the United States’ recent imposition of a 10% tariff on Chinese imports. It is not clear whether U.S. imports of the impacted minerals will qualify for licenses given China’s national security concerns and the minerals’ heavy use in U.S. defense and technology.
Anticipated Disruptions
Stakeholders should prepare for:
- Supply delays: The new licensing requirements may slow down the export process, leading to delays in receiving essential materials.
- Material shortages: Given China’s substantial share in the production of these metals, global shortages are possible until alternative sources are identified.
- Increased costs: Supply constraints may drive up prices for these metals, affecting production costs across impacted industries.
Recommendations
Stakeholders are advised to:
- Assess supply chain exposure: Identify dependencies on the restricted metals and evaluate the potential impact on operations.
- Explore alternative suppliers: Investigate other global sources for these metals or suitable substitutes to diversify supply chains.
- Communicate with customers: Proactively inform clients about potential delays or changes in product availability and manage expectations accordingly.
https://www.exiger.com/perspectives/critical-minerals-export-controls
China export curbs push European bismuth prices to highest since 2008
By Anushree Ashish Mukherjee and Ashitha Shivaprasad
February 21, 20254:39 AM ESTUpdated 5 days ago
- Summary
- China produced more than 80% of world’s bismuth last year – USGS
- Alternative producers include Korea, Japan and Laos
Feb 21 (Reuters) – Bismuth prices in Europe have soared to their highest in nearly 17 years after China’s plan to impose export curbs raised fears of curtailed supply for the metal used in medication, cosmetics and atomic research.
Earlier this month, China said it would implement export controls on five critical metals — tungsten, tellurium, molybdenum, bismuth, and indium — in retaliation to new tariffs imposed by U.S. President Donald Trump.
From $6 per lb previously, bismuth prices have surged to between $12 and $18 in the European spot market this week, the highest level since May 2008.
Traders expect to see higher bismuth prices.
China produced roughly 13,000 tons, or over 80% of the world’s supply, of bismuth last year, according to the U.S. Geological Survey (USGS).
The rest comes from countries, including Japan, South Korea and Laos. However, traders say the availability from other nations was limited compared to China.
“We have received many inquiries from both our EU and our U.S. customers,” a trader based in Europe said, adding that U.S. consumers would be more vulnerable if the China-U.S. trade war escalates.
The U.S. has been heavily reliant on imports since it stopped production of primary refined bismuth in 1997, according to the USGS.
If the U.S. was completely cut off from Chinese bismuth supplies, production outside China would have to grow by 22% to meet demand, said Jost Wubbeke, Managing Partner at Sinolytics.
“It is hard to find cheap and stable alternative supplies, especially when everyone’s trying to find new sources at the same time.”
As trade tensions escalate, China is expected to further leverage its dominance in critical minerals to retaliate.
February 16, 2025
BASF Expands MDI in China
BASF Plans for Further MDI Expansion in Shanghai, China
PUdaily | Updated: February 13, 2025
BASF Plans to Expand MDI Capacity in Shanghai to 400 ktpa
Recently, the MDI expansion project launched by Shanghai BASF Polyurethane Co., Ltd. (SBPC) is under public disclosure. According to the announcement, SBPC, located in Shanghai Chemical Industry Park, is one of the original three Sino-foreign joint ventures that initiated an integrated isocyanates plant project in Shanghai. The project was co-launched by Shanghai Lianheng Isocyanate Co., Ltd. (SLIC), Shanghai Huntsman Polyurethane Co., Ltd. (Huntsman Shanghai), and Shanghai BASF Polyurethane Co., Ltd. (BASF Shanghai). In July 2023, BASF announced that SLIC would be split between BASF Shanghai and Huntsman Shanghai. As of February 2024, the spin-off had been completed, with BASF Shanghai acquiring SLIC’s 240 ktpa crude MDI plant along with the nitrobenzene/aniline unit.
Currently, BASF Shanghai’s crude MDI capacity cannot meet demands in the surrounding markets. Therefore, the company plans to enhance production efficiency by renovating bottleneck facilities that affect the increase in production capacity per unit time. It will also extend the production time of the nitrobenzene/aniline unit and the MDA/crude MDI unit from the original 7,500 hours/year to 8,000 hours/year. Once the expansion project is completed, BASF Shanghai’s crude MDI capacity will achieve 401.76 ktpa, while its MDI splitting capacity will remain unchanged at 300 ktpa.
Furthermore, BASF’s MDI splitting capacity at its Chongqing plant is currently being expanded to 530 ktpa.
“Winning Ways” Strategy – Continuing to Increase Investment in the Asia-Pacific Region, Particularly in China
In September 2024, BASF presented its new “Winning Ways” strategy along four strategic levers: Focus, Accelerate, Transform and Win, aiming to strengthen its core businesses and add the value of standalone businesses. In order to enhance its presence in Asian markets, BASF continued to increase investments in the Asia-Pacific region, particularly in China. Apart from the MDI expansion project in Shanghai, BASF’s investment projects in China include Zhanjiang Verbund site, expanded downstream chemical plants at BASF-YPC, investments in synthetic biotech, polymer dispersions, anode binder, battery materials and renewable power. These investments underscore BASF’s long-term commitment and confidence in the Chinese market, as well as its strategic emphasis on sustainable development and high value manufacturing.
China is to Contribute Nearly 50% of Global MDI Capacity
In 2024, the global MDI capacity reached 10.69 mtpa in 2024, according to PUdaily. The MDI capacity in China was 4.69 mtpa, contributing 44% of the global total capacity. It’s projected that by 2029, the global MDI capacity will increase to around 12.84 mtpa and China’s MDI capacity will expand to 6.19 mtpa, further raising its share in the global total capacity to 48%.
January 15, 2025
Propylene Oxide in China
China Propylene Oxide & Polyols Market in January
PUdaily | Updated: January 14, 2025
In January 2025, due to the production of new facilities at Befar Group and Wanhua Chemical, these two suppliers in Shandong showed stronger intentions to clear inventory and cut prices by CNY 300/tonne. PO prices in East China dropped by CNY 100/tonne as a result. The price difference between the North and the South widened, leading to slightly varied sales performance. Meanwhile, recent import prices for PO have been continuously decreasing, with the latest offer at USD 990/tonne.

In terms of import, China’s import volume of PO has been declining in recent years and the annual import volume for 2024 is estimated to total 250 kT, marking a more than 20% decrease compared to the previous year.

As Chinese New Year approaches, downstream manufacturers are increasing purchases at relatively low prices, while the growth in new orders has been muted. Suppliers may maintain willingness to sell and negotiate. With ongoing inventory reduction, the market is projected to fluctuate slightly in the near future.
Prices for flexible slabstock polyols have moved down due to reduced costs. However, the drop in polyols prices is less than in PO prices, resulting in increased profits for polyols producers. Acrylonitrile prices have risen from CNY 9,400/tonne to CNY 10,500/tonne, causing a shrink in profits for polymer polyols. It is expected that the acrylonitrile market will remain high next week. Owing to limited supply increases and low inventories, coupled with the pre-holiday restocking blitz, the market is likely to keep resilient.
January 6, 2025
Chinese PMDI Overview
Will China’s PMDI Market Continue Its Upsurge in 2025?
PUdaily | Updated: January 3, 2025
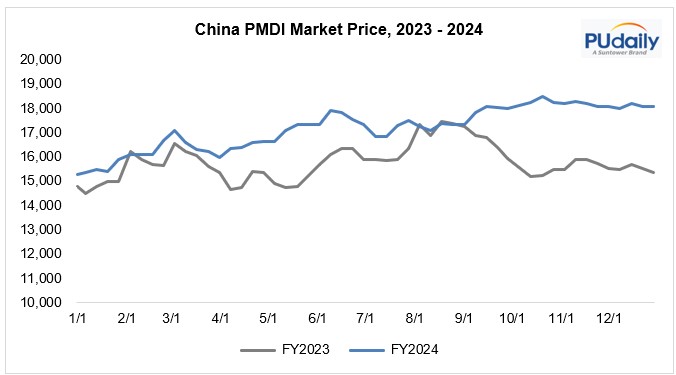
On December 31, 2024, China’s PMDI market closed at a range of CNY 18,100-18,300/tonne, reflecting a remarkable increase of CNY 2,800/tonne (+18.2%) compared to the range of CNY 15,300-15,500/tonne at the end of December 2023. The average price of PMDI in China in 2024 stood at CNY 17,200/tonne, remaining basically same with the yearly average in 2022. The market price in 2024 indicated an upward trend. In December, as most suppliers had completed sales targets and halted or reduced deliveries, PMDI supply remained tight. Many distributors had no stock nor quotations, awaiting shipments from suppliers in the upcoming month.
In Supply Side
In 2024, PMDI suppliers’ pricing strategies and inventory management practices maintained PMDI social stocks at low levels.
In February, global oil prices increased during the Chinese New Year holiday, then China benzene market followed to increase, leading to increased PMDI production costs, pushing major MDI suppliers to raise list prices, then distributors followed to increase their quotations.
However, in late February, sudden severe cold weather across several regions in China delayed resumption of production and procurement for raw materials including PMDI in downstream sectors, leading to insufficient support for PMDI price increases. PMDI prices moved down in March.
In April, as it turned warmer, demand picked up gradually in construction sectors. but PMDI supply was relatively slow, leading to further depletion of spot inventories and a rebound in PMDI prices.
The uptrend continued during May and mid-June.
The market faced a marginal retreat due to off-season factors towards the end of June until August, and picked up again from September onwards.
In November and December, the price stabilized in the range of CNY 18,000-18,500/tonne.
In Demand Side
The downstream sectors for PMDI include home appliances, building insulation, cold chain logistics, transportation., etc. Home appliance is currently the largest downstream sectors of PMDI demand markets in China. Thanks to trade-in policies and leading home appliance companies’ ambitious actions on exploring overseas markets, both domestic sales and exports of refrigerators in China saw unexpected growths in 2024, contributing to ongoing increases in refrigerator production. The growth in international trade, the upturn in container shipping segment and incidents like Red Sea Crisis brought substantial orders for Chinese reefer container and LNG carrier manufacturers. In addition, Chinese PMDI exports from January to November 2024 rose by 11.5% year on year.
Looking ahead to 2025, suppliers’ pricing and inventory management are expected to maintain stable support to the market. In terms of demand, China set top of key tasks for 2025 at the Central Economic Work Conference as “vigorously boosting consumption, improving investment efficiency and expanding domestic demand on all fronts”. The conference prioritized supporting expanding domestic demand, particularly in consumer demand, which in turn will have a positive effect on industries like automobiles and home appliances. Furthermore, as 2025 marks the conclusion of China’s 14th Five-Year Plan (2021-2025), most market participants are observing the support given by the national and local governments in infrastructure projects. Despite market concerns about the risks associated with U.S. tariffs, which may impact on PMDI prices and export business of PMDI-based products from China to the U.S., Chinese PMDI market is projected to continue its upsurge driven by bullish factors in both supply and demand sides.
December 15, 2024
Tosoh to Expand Production Capacity to Meet Growing Demand for High-Performance Paint Hardeners
NEWS RELEASE
December 3, 2024
Tosoh to Expand Production Capacity to Meet Growing Demand for High-Performance Paint Hardeners
Tokyo, Japan—Tosoh Corporation plans to increase its production capacity for hexamethylene diisocyanate (HDI) derivatives at its Nanyo Complex in Shunan City, Yamaguchi Prefecture. The company markets its HDI derivatives under the Coronate brand.
HDI derivatives are advanced functional polyurethanes widely used as paint hardeners and are integral products in the company’s Specialty business portfolio. They are valued for their superb resistance to yellowing and weathering, which makes them essential as high-performance hardeners in automotive and architectural exterior coatings.
Tosoh’s expansion of its production capacity for HDI derivatives responds to the robust growth of the global coatings market, propelled by steady demand in developed economies, increasing demand in emerging markets amid heightened motorization, and rising demand in worldwide markets amid elevated infrastructure investments. Industry projections indicate growing demand for HDI derivatives.
The increase to HDI derivatives production capacity is thus a strategic move by Tosoh to position itself to capitalize on growing demand for and to ensure the stable supply of HDI derivatives. The company intends to significantly expand the scale of its business in HDI derivatives to increase corporate profitability. Tosoh, meanwhile, is committed to meeting the evolving needs of its customers and thus contributes to advancements in coating technologies for diverse industries.

 Everchem Updates Archive
 Sign Up for Email Updates