
Current Affairs
October 13, 2025
Container Rates
Surprise move by China carriers ahead of U.S. port fees
Weak demand sees trans-Pacific container rates fall by double-digits.
· Wednesday, October 08, 2025

It took China a generation to ascend to the top of the global maritime sector; it won’t take nearly that long for that country to brush off expensive U.S. port fees on its ships.
Cosco, China’s flag carrier and the world’s fifth-largest container line, and subsidiary Orient Overseas Container Line (OOCL) of Hong Kong said that they won’t levy surcharges to offset the fees on Chinese-built and operated ships calling U.S. ports to be implemented Oct. 14.
While other liner operators scramble to drop calls and shift some of their China tonnage, Cosco advised customers in the U.S. that it plans no changes to services ahead of the punitive fees formulated under the authority of the United States Trade Representative.
“It seems unlikely shippers will experience much of an impact once the new law takes effect,” said Judah Levine of analyst Freightos, in a note to clients.
The fees, which escalate in the coming years, could cost Cosco and OOCL as much as $2.1 billion in 2026, analysts say, but could be absorbed by subsidies from Beijing.
The ship tax, which aims to blunt China’s maritime dominance and boost American shipping and shipbuilding, charges China-owned or operated ships $80 per net tonnage for each voyage to the U.S. Non-Chinese operators will be charged the greater of $23 per net ton or $154 per twenty-foot equivalent unit (TEU) capacity. The fees apply up to five times annually per vessel; roll-on/roll-off (ro-ro) vehicle carriers will pay a rate of $14 per net ton. The fees increase by $5 per ton annually until April 2028.
The fees must be paid in advance of arrival via the Treasury Department’s Pay.gov platform, and vessels must show proof of payment or risk denial of entry or cargo operations at U.S. ports.
Beijing for its part in late September passed new maritime laws that allow it to levy its own retaliatory port fees, and bar access to ports and data for vessels from countries that discriminate against China.
“American lines such as Matson, and U.S.-flagged vessels make up a modest share of trans-Pacific volumes,” said Levine, “so this kind of response may not have an outsized impact, but does represent an escalation as the deadline approaches.”
Trans-Pacific spot container rates continued to fall following the Chinese Golden Week holiday. The Freightos Baltic Index saw Asia-U.S. West Coast rates drop 16% to what Levine termed “a possibly loss-making” $1,554 per forty foot equivalent unit (FEU). Prices to the East Coast fared worse, off 18% to $3,260 per FEU.
Asia-Europe settled at $2,000 per FEU, down 9%, and Asia- Mediterranean prices fell 6% to $2,217 per FEU, “with all these lanes at least 60% lower than this time last year and at or near their lowest levels since just before the start of the Red Sea crisis almost two years ago,” Levine said.
“That rates are falling to this degree while Red Sea diversions are still in place suggests that capacity growth is a big factor in lower rates across the industry,” said Levine, “with the eventual end of the war in Gaza primed to release even more capacity back into the market.”
Ocean container lines introduced approximately 1.18 million TEUs of new container shipping capacity in the first half of 2025, according to analyst Xeneta, up 3.8% from a year ago.
Whether general rate increases planned by carriers for mid-October hold could depend on capacity adjustments through blankings and service suspensions. October shows 67 sailings cancelled from China to the U.S. and 71 on the westbound trade, according to project44, higher than early-Covid levels.
October 12, 2025
Words of Wisdom
INTERVIEW: US mattress market is recovering from H1 lull
Al Greenwood
07-Oct-2025

ST LOUIS (ICIS)–US production and sales of mattresses have started recovering during the second half of 2025, the CEO of Carpenter said on Tuesday.
The recovery started during the Fourth of July holiday, and it has persisted through Labor Day in September, said Brad Beauchamp, CEO of Carpenter, a US producer of polyurethane foams and polyols as well as mattresses under its Casper Sleep business.
Beauchamp made his comments in an interview with ICIS on the sidelines of the Polyurethanes Technical Conference, hosted by the Center for the Polyurethanes Industry (CPI).
Part of the rebound reflects the surge in imports that took place prior to the imposition of tariffs from the US, he said. The market has since worked down those imports.
Tariffs could also be boosting domestic market, given the cessation of the de minimis exemption.
The recovery in demand for mattresses is happening from a low base, Beauchamp said. Earlier in the decade, demand had fallen following the surge of buying that happened during the COVID-19 pandemic.
The slowdown in housing sales further depressed demand. Consumers tend to buy bedding when they move, and fewer home sales mean that consumers are moving less.
US house construction remains slow, and economists do not expect a recovery until the end of 2026.
Furniture demand is still struggling, Beauchamp said. Imports had not increased to the same extent as those for furniture, so order patterns were less volatile than those for mattresses.
At times, domestic furniture plants are operating under shortened work week, Beauchamp said.
Together, furniture and mattresses make up 35% of demand for polyurethanes, making them the largest single market, according to ICIS.
CARPENTER SEES EARLY SIGNS OF FUTURE FURNITURE RESHORING
Furniture producers have started making inquiries that could lead to some companies’ reshoring their production to the US, Beauchamp said. While furniture is labor intensive, its bulk and shape make it difficult to ship overseas.
Reshoring interest started before the recent US tariffs because of a series of logistical disruptions caused by bad weather, the COVID-19 pandemic and low water levels at the Panama Canal.
Ashley Furniture is expanding capacity in Lee County, Mississippi, state, according to a mid-2024 announcement by the Mississippi Development Authority.
Recent US tariffs have strengthened this larger trend.
There have been fewer inquiries to reshore mattresses because they are easier to ship, Beauchamp said.
TARIFFS DISRUPTIONS DUE MOSTLY TO UNCERTAINTY
The effects that tariffs have had on Carpenter are mostly due to the uncertainty they have created among businesses and consumers, Beauchamp said.
Like many companies, Carpenter has seen few direct effects outside of isolated ones such as textiles for mattress covers.
The Polyurethanes Technical Conference runs through Wednesday.
Interview article by Al Greenwood
October 9, 2025
Spot Truck Rates
How truck spot rates are shifting
Tracking the changes to dry van, reefer and flatbed truck freight rates provides a window into the state of the market.
Updated an hour ago
Tracking the latest trucking spot rates can help trucking executives and shippers alike anticipate future contract rates and needs.
These highlights for national spot rates come from data from DAT Freight & Analytics, measuring a weekly moving average that excludes a fuel surcharge.
While rates surged when the COVID-19 pandemic caused demand to spike, the industry has subsequently been stuck in weaker conditions for about two years. Because rates are constantly shifting, Trucking Dive is working with DAT to bring readers frequent insights into how spot rates are shifting.
Scroll further for a deeper look at trends since 2019, in a chart, as well as frequent updates below.

https://www.truckingdive.com/news/truck-freight-rates-changes-tracker/715709/
September 29, 2025
India Polymer Polyol ADD
India Imposes ADD on Chinese Copolymer Polyol Following DGTR Investigation
PUdaily | Updated: September 29, 2025
On September 26, 2025, the Indian government took steps to protect its domestic chemical industry from unfairly traded imports, announcing definitive anti-dumping duties on a key polymer imported from China. The decision follows an extensive investigation by the Directorate General of Trade Remedies (DGTR), which found evidence of significant dumping causing material injury to a local producer.
The duties apply to imports of “Copolymer Polyol of hydroxyl value >= 23.5” (HS Codes 3907 2910 and 3907 2990), a chemical primarily used in the production of flexible foam for mattresses and other applications. The DGTR clarified that Polyester Polyol of the same grade is excluded from this measure.
The investigation, initiated in September 2024, concluded that imports from China were entering the Indian market at dumped prices, with margins ranging from 20% to over 50%. This unfair pricing undercut domestic sales and severely harmed the financial health of the sole Indian manufacturer, M/s Expanded Polymer Systems Pvt. Ltd.
The following key findings from the investigation formed the basis for the final determination:
- Massive Import Surge & Market Displacement: Import volumes from China surged by 287% (from 4,988 to 19,338 MT), seizing over 90% of the total import market. This massive influx displaced traditional suppliers from Europe and the USA and severely eroded the domestic industry’s market share.
- Significant Price Undercutting & Suppression: The landed value of Chinese imports was consistently 10-20% below the domestic industry’s price. This forced the domestic producer to suppress its prices below its own cost of sales for the entire period, directly preventing profitability.
- Severe Financial Injury: Despite a 96% growth in domestic demand, the domestic company operated at a loss with negative returns. Its capacity utilisation was critically low at around 32%, while inventories swelled by 137%, confirming financial distress due to unfair competition.
- Causal Link Established: The Authority definitively ruled out other factors like demand contraction or technological changes, concluding that the surge of low-priced, dumped imports was the primary cause of the material injury.
In its final findings, the DGTR affirmed that Expanded Polymer Systems Pvt. Ltd. constitutes a valid ‘domestic industry’ and that a direct causal link exists between the dumped imports and the injury suffered.
Recommended Anti-Dumping Duties
The DGTR has recommended the following duties (CIF value in USD per Metric Tonne) for a period of five years:
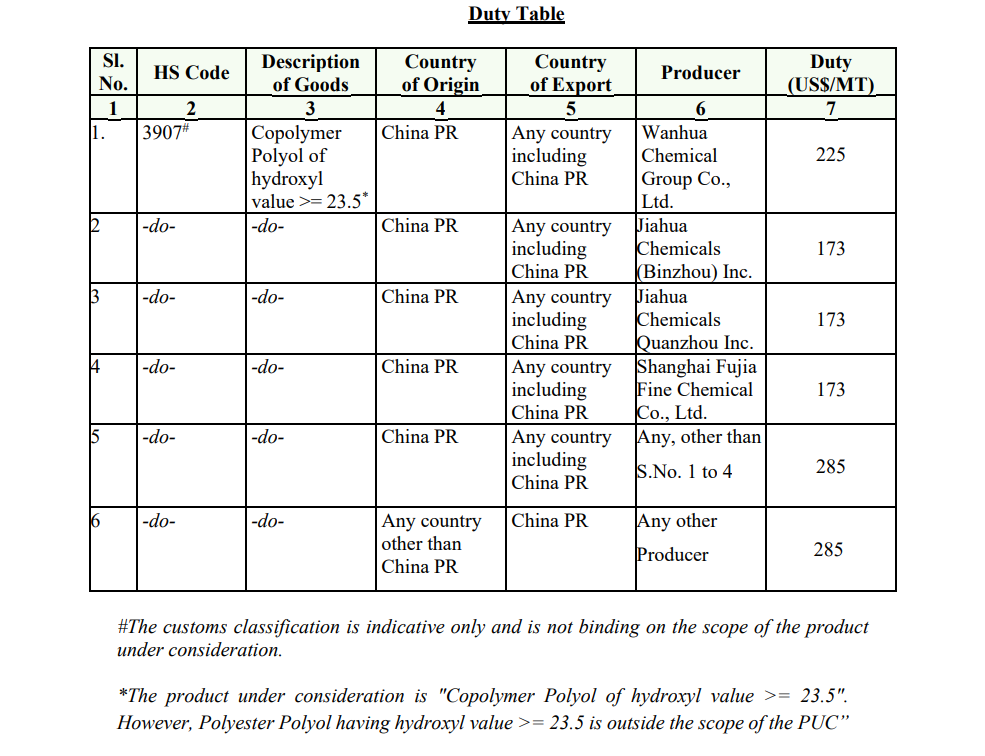
The authority stated that the imposition of these duties aligns with the World Trade Organisation’s (WTO) framework and aims to restore fair competition in the Indian market. It emphasised that the measures are not intended to restrict imports but to ensure they enter India at non-injurious prices, thereby safeguarding the interests of the domestic industry.
India’s Ministry of Finance will issue the final notification for the imposition of these duties.
September 25, 2025
New Home Sales in August
Housing Shock: New-Home Sales Unexpectedly Soar 20%
24 Sep 2025270
4:05
New-home sales surged in August to their strongest pace in more than three years, as aggressive price cuts and incentives by builders successfully drew buyers back into a housing market that had been stalled by high mortgage rates and elevated prices.
Sales of new single-family homes increased to a seasonally adjusted annual rate of 800,000 units, a 20.5 percent increase, the Commerce Department and Housing and Urban Development Department said Wednesday.
The pace was well above the 653,000 rate economists had forecast and marked the fastest selling pace since early 2022.
The unexpected jump suggests that homebuilders’ strategy of offering steep discounts and sales incentives is working to revive demand in a market where many potential buyers had been sidelined by affordability concerns. The robust sales pace also helped reduce the inventory overhang that had been weighing on the sector.
The sales surge was broad-based, with gains across all major regions. The South, which accounts for the largest share of new-home sales, saw purchases jump 24.7 percent to 530,000 units. The Northeast posted the largest percentage gain at 72.2 percent, though from a much smaller base.
Builder incentives have reached post-pandemic highs as companies seek to move inventory. Some 39 percent of builders reported cutting prices in September, according to a survey by the National Association of Home Builders and Wells Fargo—the highest level since the early days of the Covid-19 pandemic.
The sales increase helped reduce the supply of unsold new homes to 490,000 units at the end of August, the lowest level this year. That translates to 7.4 months of supply at the current sales rate, down sharply from 9.0 months in July. While still above the 4-to-6 month range considered normal, the improvement suggests the market is moving toward better balance.
The median price of a new home sold in August was $413,500, up 4.7 percent from July but only 1.9 percent higher than a year earlier. The average sales price of $534,100 was up 11.7 percent from the previous month and 12.3 percent higher than August 2024, suggesting strength at higher price points.
By subscribing, you agree to our terms of use & privacy policy. You will receive email marketing messages from Breitbart News Network to the email you provide. You may unsubscribe at any time.
New-home sales reflect contract signings rather than closings, making them a more timely indicator of buyer sentiment than existing-home sales. The August figures likely captured the beginning of a recent decline in mortgage rates, which have since fallen to their lowest levels in more than a year.
The government also revised sales figures for the previous three months higher, suggesting the housing recovery has been building momentum. Sales data is subject to large revisions due to the survey methodology and relatively small sample size.
Despite the improved August numbers, the housing market continues to face headwinds from mortgage rates that remain elevated by historical standards and home prices that have priced out many potential buyers. The average rate on a 30-year fixed mortgage was about 6.2 percent in August, down from peaks above 7 percent last year but still well above pre-pandemic levels.
Shares of major homebuilders rose in early trading Wednesday. Lennar gained 1.99 percent, D.R. Horton rose about one percent. and PulteGroup climbed 1.65 percent.
The new-home market represents a small fraction of overall housing activity but is closely watched as an indicator of future labor intensive construction activity and broader housing demand. What’s more, rising new home sales often have coattails, boosting furniture, technology, and appliance sales. New homes accounted for about 15 percent of home sales in recent months.
https://www.breitbart.com/economy/2025/09/24/housing-shock-new-home-unexpectedly-soar-20
 Everchem Updates Archive
 Sign Up for Email Updates